Establish a credible European company within a stable legal system, advanced economy and strategically connected Central European market.
Austria offers international entrepreneurs and corporate groups a well-regulated environment for establishing and operating a business within the European Union. Its central location, developed infrastructure, skilled workforce and close commercial links with Central and Eastern Europe make it suitable for companies seeking a credible regional base. The jurisdiction is particularly relevant for international trading groups, industrial businesses, technology companies, professional service providers, holding structures and enterprises expanding into multiple European markets. Austria should not be viewed merely as a registration destination. Successful company formation requires coordinated planning across corporate law, trade licensing, taxation, banking, beneficial ownership, employment and operational substance. Foreign investors can generally own Austrian companies, although sector-specific restrictions, investment screening rules and licensing requirements may apply. The selected legal form and governance structure should therefore reflect the company’s actual commercial activities, ownership model and long-term objectives.
Austria combines European market access with institutional stability, specialised talent and highly developed commercial infrastructure.
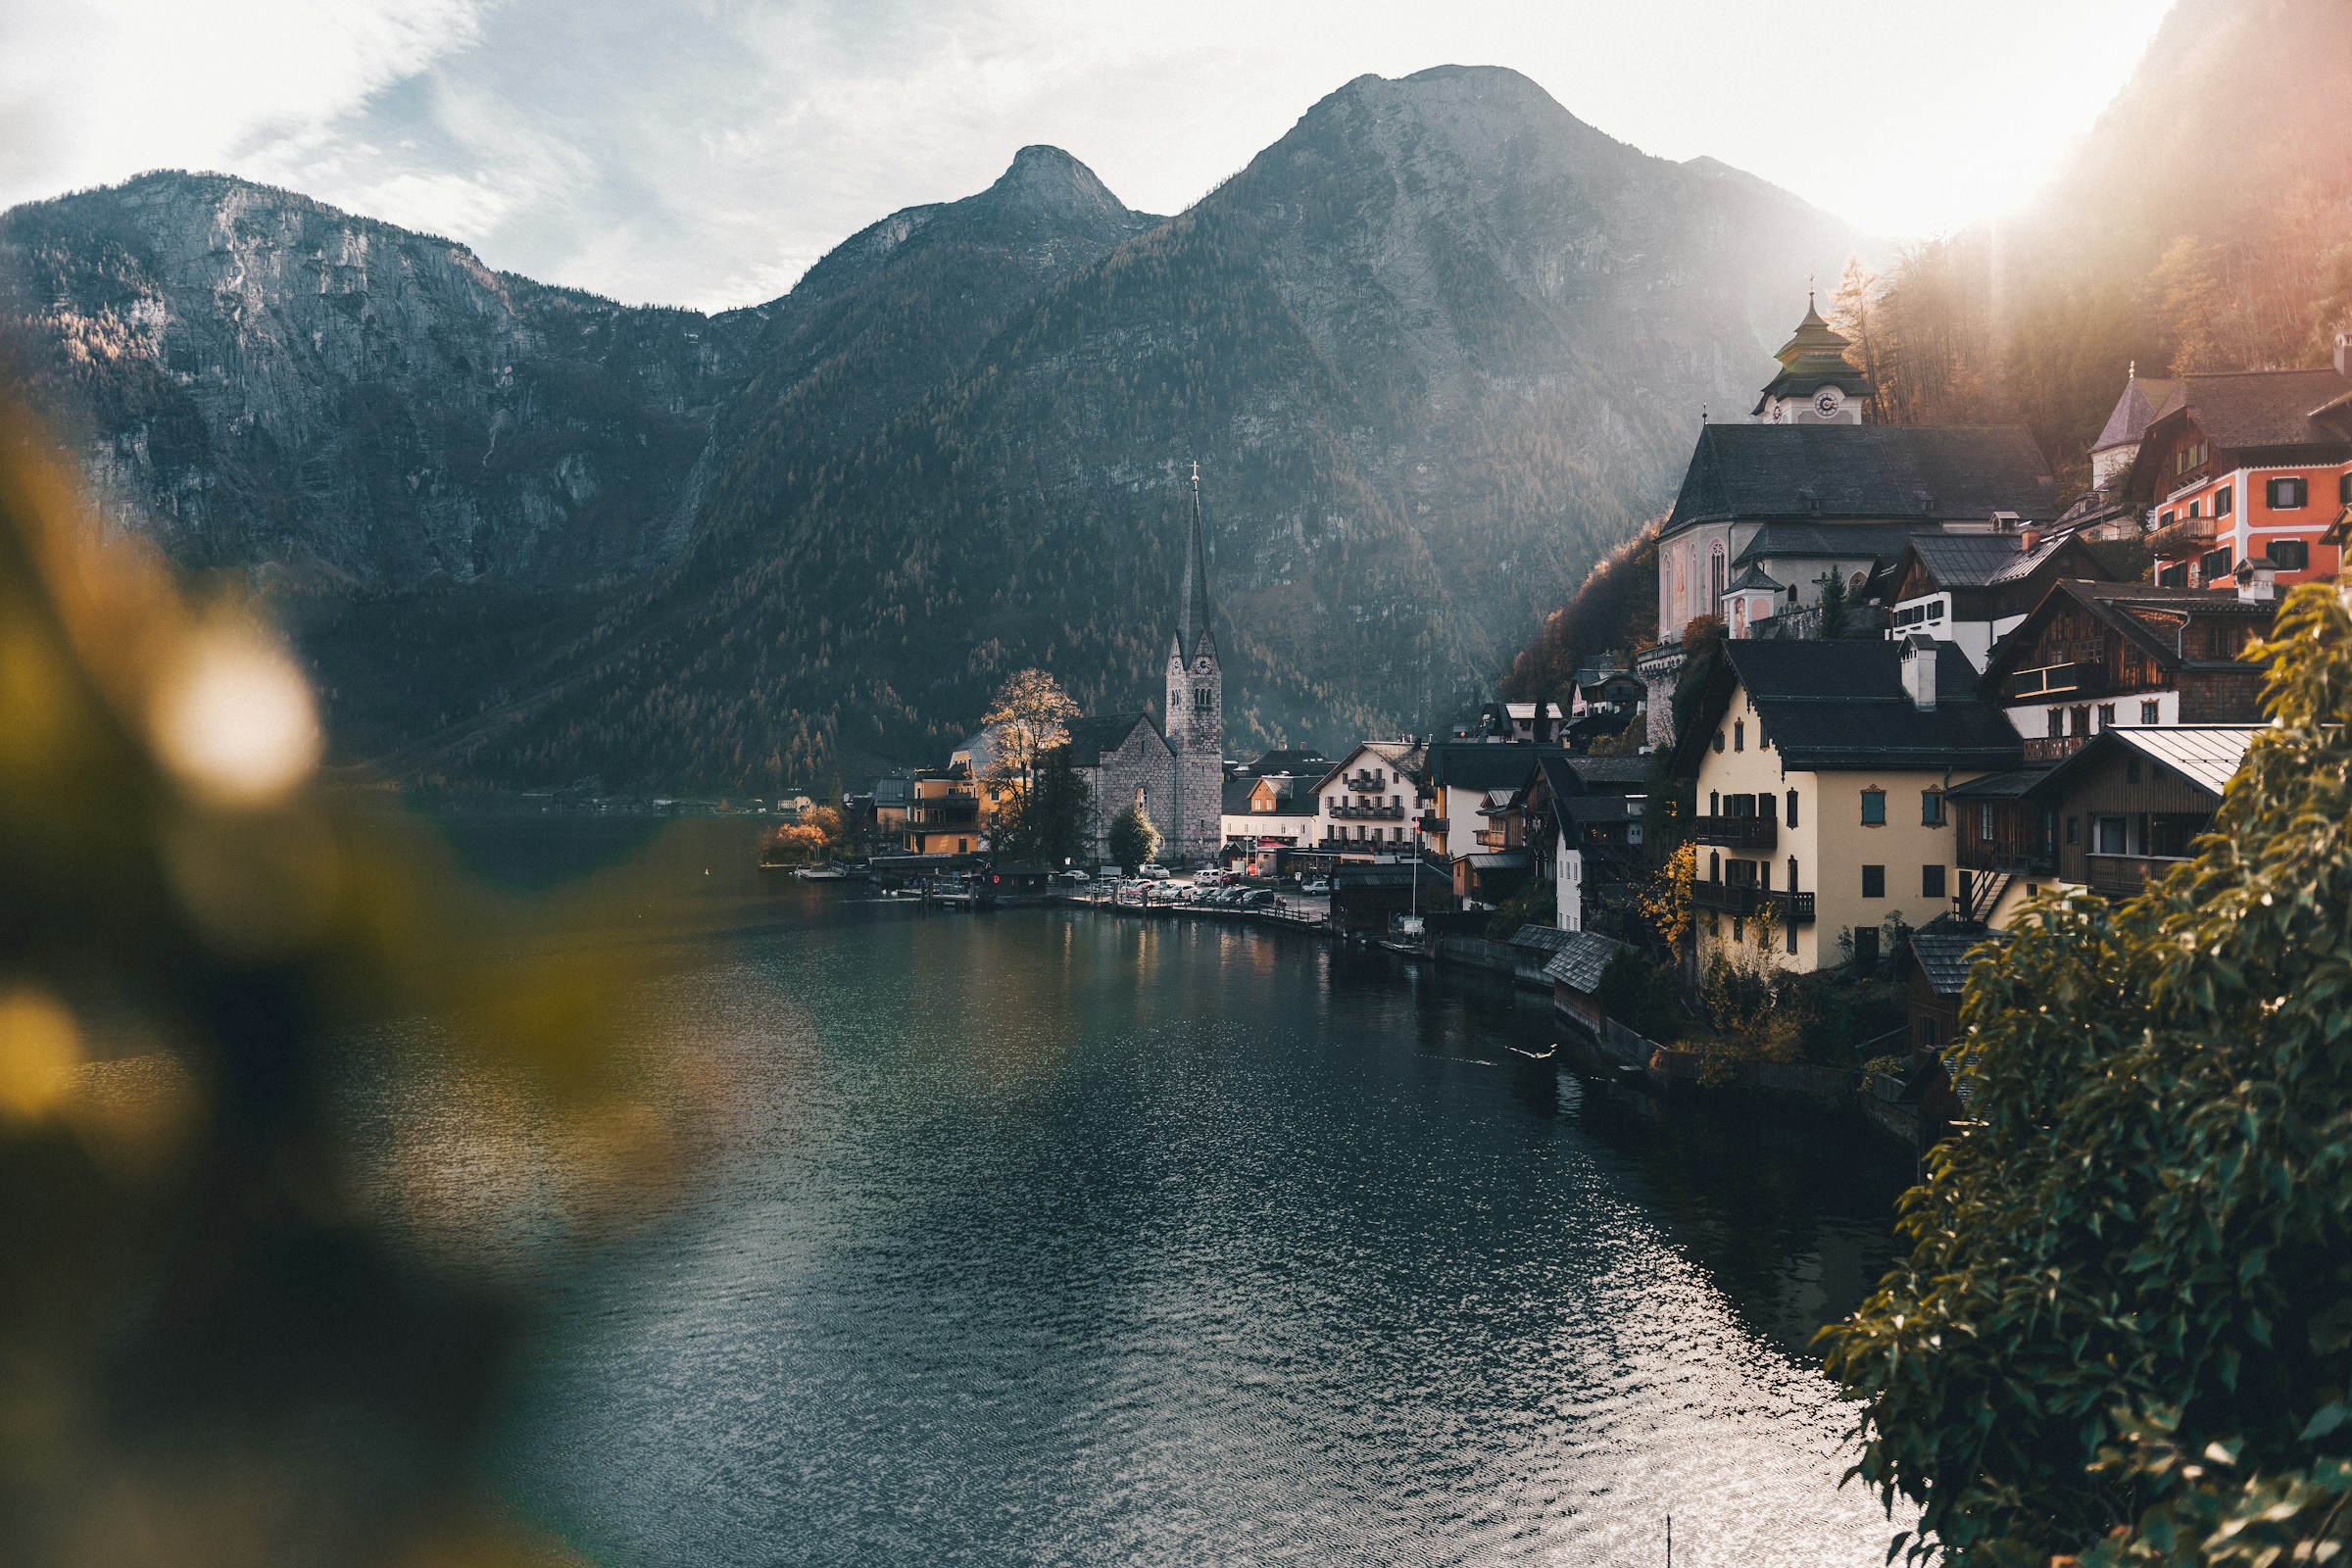
Austria is located at the centre of Europe and shares borders with Germany, Switzerland, Italy, Slovenia, Hungary, Slovakia, the Czech Republic and Liechtenstein. This position supports commercial access to both established Western European economies and developing markets across Central and Eastern Europe.
As a member of the European Union and the euro area, Austria provides businesses with access to the EU internal market, common commercial standards and an internationally recognised legal and financial environment.
Vienna is widely used as a regional headquarters location, particularly by companies managing operations across Germany, the Balkans, Central Europe and Eastern Europe. Other Austrian regions offer specialised industrial clusters, logistics infrastructure, technical expertise and links with neighbouring markets.
Austria’s road, rail, air and inland waterway networks support cross-border logistics and distribution. Businesses trading within the European Union can also benefit from harmonised customs and product frameworks, although VAT, reporting, product compliance and origin requirements must still be managed correctly.
The legal form determines the company’s liability, capital requirements, governance, tax treatment, financing options and administrative responsibilities.
The principal structures available to international founders include:
The GmbH remains the standard choice for most privately owned businesses. A FlexCo may be more suitable for startups, technology companies and businesses requiring flexible ownership or employee participation arrangements.
An AG is generally used for larger enterprises, institutional investment structures and companies seeking access to capital markets. Partnerships may be appropriate for professional practices or closely held businesses, while a branch can allow a foreign company to operate in Austria without forming a separate Austrian subsidiary.
The decision should be based on the planned business model rather than registration cost alone.
The Austrian GmbH is a separate legal entity with liability generally limited to the company’s assets. It can be established by one or more individual or corporate shareholders, including foreign shareholders.
A GmbH requires minimum share capital of EUR 10,000. As a general rule, at least EUR 5,000 must be paid in cash during formation, subject to the structure of the contributions and the company’s constitutional documents.
The company is managed by one or more managing directors. Their authority, appointment and removal are governed by Austrian corporate law, the articles of association and shareholder resolutions.
The articles normally address:
The GmbH is suitable for trading companies, subsidiaries, consulting businesses, industrial operations, holding companies and owner-managed enterprises.
Austria introduced the Flexible Company, commonly referred to as the FlexCo, in 2024. It combines elements of the traditional GmbH with more adaptable governance and participation mechanisms.
The FlexCo can be used by businesses of any size, but it is particularly relevant to startups and growth companies that expect multiple investment rounds, employee participation or changes in ownership.
Its possible advantages include:
Like the GmbH, the FlexCo generally requires minimum share capital of EUR 10,000.
The FlexCo should not automatically be selected simply because it is newer. Its articles of association, voting arrangements, investor protections, founder rights and exit provisions require careful drafting.
A GmbH or FlexCo acquires legal personality when it is entered in the Austrian Commercial Register, known as the Firmenbuch.
The formation process generally includes:
Banks, notaries and registry authorities may request identification documents, corporate extracts, powers of attorney and information about the source of funds.
Foreign corporate documents may need to be legalised or apostilled and accompanied by certified German translations.
The expected formation period depends on the legal form, ownership chain, banking process, document quality and whether the intended activity is regulated.
Commercial Register entry does not automatically authorise every business activity.
Many activities in Austria fall under the Trade Regulation Act and require registration in the Austrian Business Licence Information System, known as GISA. Certain regulated trades also require proof of professional qualifications or the appointment of a qualified managing director under trade law.
Activities that may require additional analysis include:
A company should determine its licensing position before signing premises, hiring staff or entering into client contracts. Operating without the correct authorisation can result in penalties and business interruption.
Austrian companies are subject to beneficial ownership transparency requirements under the Austrian Beneficial Owners Register Act, commonly known as WiEReG.
The company must identify the individuals who ultimately own or control it. This analysis may extend through several levels of corporate shareholders, trusts, partnerships or other legal arrangements.
The company may need to retain and report information concerning:
Some entities may qualify for reporting exemptions where the required information is already available through Austrian public registers. However, the exemption must be confirmed rather than assumed.
Beneficial ownership records should be reviewed whenever the ownership structure, voting rights or control arrangements change.
Austrian resident companies are generally subject to corporate income tax at a standard rate of 23% on their taxable profits.
Tax residence may arise where a company has its registered office or place of effective management in Austria. International structures must therefore consider where strategic decisions are taken and where the company’s management is genuinely exercised.
Austria’s standard VAT rate is 20%. Reduced rates can apply to specified goods and services, including certain food products, publications, accommodation and cultural activities.
VAT registration may be required when the company:
VAT treatment depends on the nature of the transaction, customer status, movement of goods and place-of-supply rules.
Other tax matters can include withholding tax, payroll taxes, municipal charges, real estate transfer tax, stamp duties and minimum corporate income tax requirements.
Austria maintains an extensive network of double-taxation treaties. EU directives may also provide relief for qualifying cross-border dividends, interest payments and corporate reorganisations. Such relief is not automatic and may depend on beneficial ownership, holding periods, legal form, tax residence, substance and anti-abuse provisions.
An Austrian corporate bank account is normally required during the formation of a GmbH or FlexCo to deposit the company’s share capital. A separate operating account is then used for commercial transactions.
Account approval is not guaranteed by company registration. Austrian and European banks apply detailed anti-money laundering and customer due diligence procedures.
Banks may request:
Applications involving complex ownership chains, high-risk countries, regulated industries or limited Austrian substance may require enhanced review.
The banking strategy should be considered before incorporation. The ownership structure, business model, countries of operation and projected transactions should be presented consistently across the corporate, tax and banking documentation.
Foreign investors can generally establish and own Austrian companies. However, investments by non-EU investors in certain sensitive sectors may be subject to Austrian foreign direct investment screening.
Relevant sectors can include:
The application of investment screening rules depends on the investor, ownership percentage, target company, transaction structure and sector involved.
Separate regulatory approvals may also apply to banking, insurance, investment services, telecommunications, pharmaceuticals, aviation and other controlled activities.
Regulatory analysis should therefore be completed before acquiring an existing Austrian business or establishing a company in a sensitive industry.
Austria has a diverse economy supported by advanced manufacturing, industrial engineering, technology, logistics, life sciences, renewable energy, tourism and professional services.
The jurisdiction is particularly recognised for:
Eligible businesses may have access to investment grants, research incentives, innovation funding, public loans or guarantees. Availability depends on the project, region, company size, technology, employment impact and funding programme.
Public support should normally be assessed before the relevant investment is made. Applications submitted after project commencement may not qualify.
An Austrian company should have sufficient operational substance for its stated functions.
Appropriate substance may include:
A registered address alone may not support claims of Austrian tax residence, treaty entitlement or genuine operational presence.
Transactions with related companies must be conducted on arm’s-length terms. Management fees, loans, royalties, distribution arrangements and service charges should be supported by written agreements, transfer-pricing analysis and evidence that the services were actually provided.
International groups should coordinate Austrian company formation with their wider transfer-pricing, controlled foreign company, permanent establishment and withholding tax positions.
Hiring employees in Austria creates payroll, social security, employment law and workplace compliance obligations.
The company may need to consider:
Collective bargaining agreements play an important role in Austria and may determine salary levels and other employment conditions for specific sectors.
Foreign ownership of an Austrian company does not itself provide the right to live or work in Austria. Non-EU directors, founders and employees may require appropriate residence and work authorisation.
Companies processing personal data must also comply with the EU General Data Protection Regulation and Austrian data protection legislation.
An Austrian company must maintain its legal, accounting and tax position after incorporation.
Typical continuing obligations include:
Audit requirements depend on the company’s size, legal form, public-interest status and applicable financial thresholds.
Corporate changes should be documented promptly. Delayed filings can affect banking, contractual due diligence, financing transactions and the company’s good standing.
Austria may be suitable for:
The jurisdiction is particularly attractive to businesses that value institutional credibility, commercial stability and integration with the European market.
Austria may be less suitable for founders seeking a low-cost, minimal-substance or lightly regulated company. Its advantages are strongest when the business intends to establish genuine operations and maintain structured compliance.
CFA Intelligence assists international founders, investors and corporate groups with the coordinated establishment and administration of Austrian companies.
Our support may include:
Each Austrian structure should be designed around the company’s ownership, activities, target markets, regulatory exposure and expected transaction flows.
Contact CFA Intelligence to discuss whether Austria is the appropriate jurisdiction for your European business operations.
Additional perspectives on international structuring,banking, compliance and regulatory developments.