Establish a credible North American business within a stable legal system, sophisticated financial market and globally connected commercial environment.
Canada provides international entrepreneurs, investors and corporate groups with access to one of the world’s most developed and respected business environments. Its combination of political stability, transparent regulation, advanced infrastructure, skilled professionals and close integration with the United States makes the country an attractive location for both operational companies and regional headquarters. The jurisdiction supports businesses across technology, financial services, advanced manufacturing, energy, natural resources, life sciences, logistics, agriculture, professional services and e-commerce. Canadian companies can also benefit from an extensive network of international trade agreements connecting the country with markets across North America, Europe and the Asia-Pacific region. However, establishing a Canadian company requires more than selecting a corporate name and filing incorporation documents. Canada operates through a federal system in which corporate, tax, employment and licensing obligations may arise at both federal and provincial levels. The appropriate structure therefore depends on where the company will operate, where its customers and employees are located, how it will be managed and whether foreign investment restrictions apply to the proposed activity.
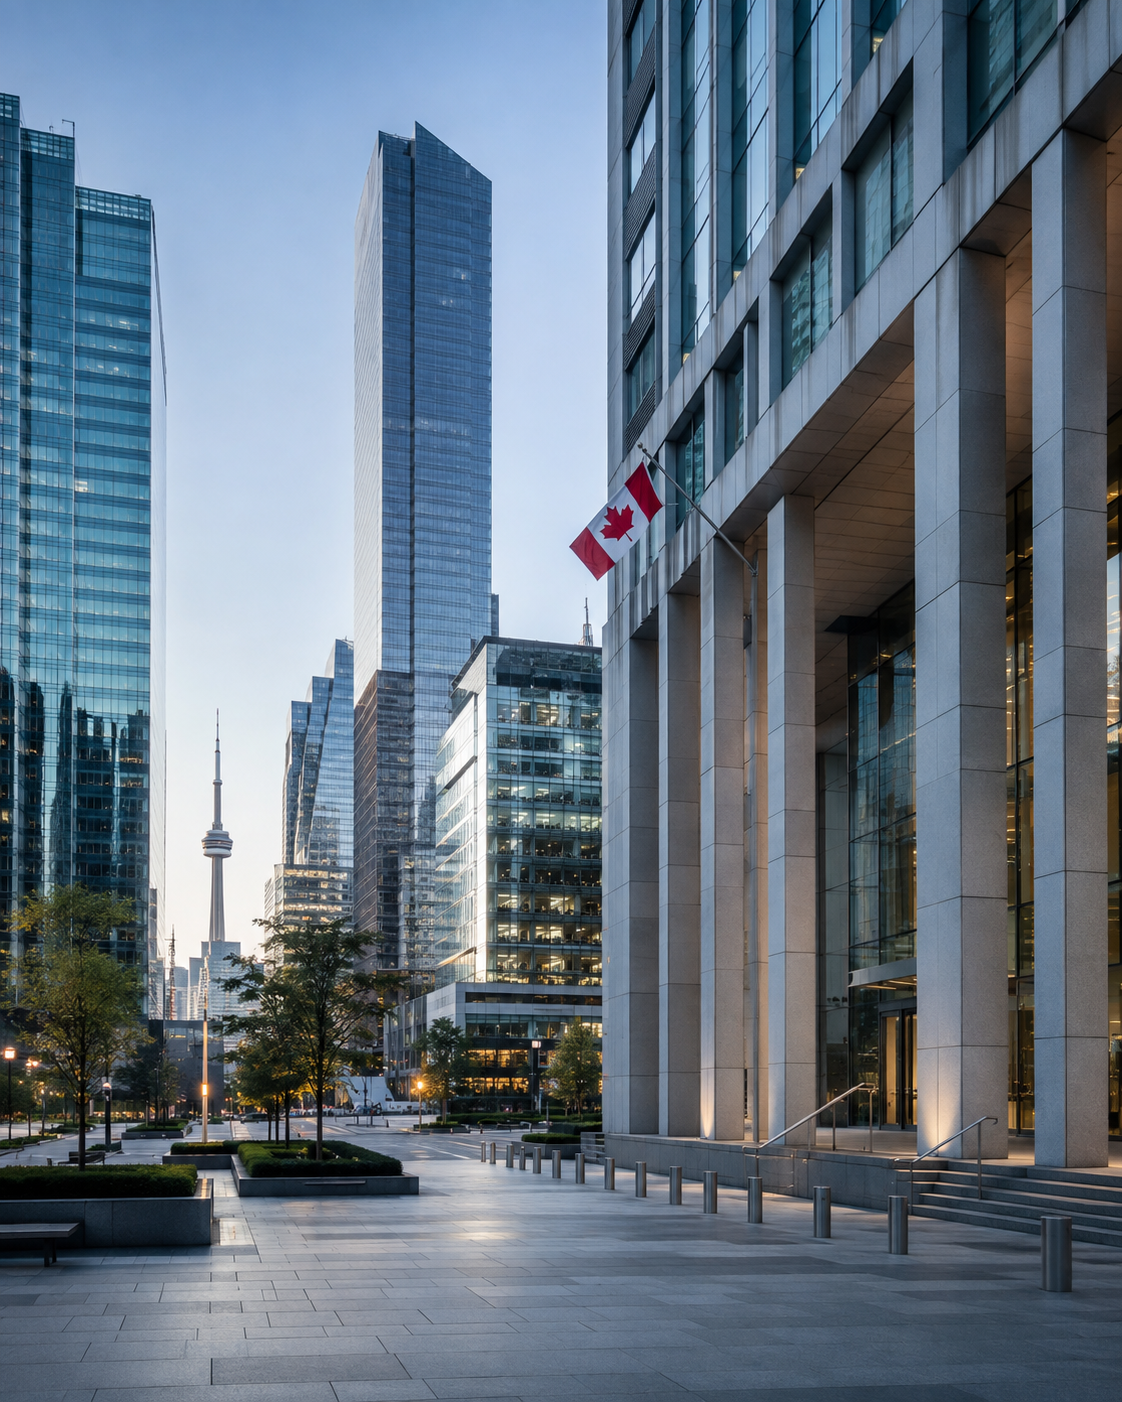
Canada combines institutional credibility, regional market access and a diversified commercial economy.
Canada offers direct access to a large domestic economy and exceptionally close commercial connections with the United States. The two countries maintain deeply integrated supply chains across manufacturing, energy, technology, agriculture, transportation and professional services.
Through the Canada-United States-Mexico Agreement, qualifying Canadian businesses may access important opportunities across the wider North American market. Canada also participates in major trade arrangements with the European Union and Asia-Pacific economies.
These agreements can support international expansion, but benefits are not automatic. Preferential tariff treatment normally depends on product classification, rules of origin, documentation and customs compliance. Incorporating a company in Canada alone does not make every product eligible for preferential treatment.
Canada’s geography also creates several distinct commercial centres. Toronto is a major financial and technology hub. Vancouver provides strong Asia-Pacific connections. Montreal is recognised for aerospace, artificial intelligence, life sciences and creative industries. Calgary supports energy, engineering and clean technology, while Waterloo has developed a significant technology and research ecosystem.
The appropriate location should be selected according to customers, talent, logistics, taxation, language requirements and sector-specific regulation.
A company may generally be incorporated under the federal Canada Business Corporations Act or under the legislation of a particular province or territory.
Federal incorporation can provide broader corporate name protection and may be appropriate for businesses intending to operate across several Canadian provinces. It also creates a corporation governed by a nationally recognised corporate statute.
Nevertheless, federal incorporation does not eliminate provincial obligations. A federally incorporated company may still need to complete extra-provincial registration in each province or territory where it conducts business.
Provincial incorporation can be suitable when the company expects to operate primarily within one province. Ontario, British Columbia, Alberta and Quebec are among the most frequently considered jurisdictions, although every province and territory maintains its own corporate framework.
The decision should consider:
Director eligibility and residency rules should always be confirmed under the selected statute because requirements are not uniform across all Canadian jurisdictions.
The corporation is the most common structure for international businesses establishing a permanent Canadian presence. A corporation is a separate legal entity and can generally own assets, enter into contracts, employ personnel, open accounts and assume liabilities in its own name.
A foreign group may establish a Canadian subsidiary, acquire an existing Canadian company or register a foreign corporation to operate through a Canadian branch.
A subsidiary generally provides clearer legal separation between the Canadian operation and its foreign parent. This can support local contracting, employment, banking and risk management.
A branch may be appropriate for certain limited or specialised activities, but it does not create the same separation. Obligations incurred by the branch can generally remain obligations of the foreign company. Branch operations may also create additional tax, registration and financial reporting considerations.
Partnerships, limited partnerships and unlimited liability companies can be useful in specialised investment or cross-border tax structures. These arrangements require individual legal and tax analysis and should not be selected solely because of their potential treatment in another jurisdiction.
Canadian incorporation is generally efficient when the required information and corporate structure have been prepared in advance.
The formation process normally includes:
The articles determine important aspects of the company’s legal structure, including its name, share classes, restrictions and number of directors. These provisions should be drafted with future ownership, investment and financing requirements in mind.
After incorporation, the company should establish its corporate minute book, bylaws, shareholder register, director register and beneficial ownership records. Share issuances and transfers should be formally approved and correctly documented.
Incorporating a company does not automatically give a shareholder, director or employee the right to live or work in Canada. Immigration and work authorisation must be considered separately.
Corporations incorporated under the federal Canada Business Corporations Act must identify and maintain information concerning their individuals with significant control.
An individual may qualify based on share ownership, voting rights, control in fact or another form of direct or indirect influence over the corporation.
Federal corporations must file relevant ISC information with Corporations Canada, including when filing the annual return. Certain information may become publicly accessible through the federal corporate registry.
The company must therefore understand its complete ownership and control chain, including situations involving:
Incorrect or outdated ownership information can create corporate, banking and regulatory problems. Beneficial ownership records should be reviewed whenever the ownership or control structure changes.
Provincial companies may be subject to separate transparency registers and beneficial ownership requirements under the relevant provincial legislation.
Canada is not a zero-tax jurisdiction. Canadian companies can be subject to both federal and provincial or territorial corporate income tax.
The general federal net corporate income tax rate is 15 percent. A provincial or territorial rate is then added according to the jurisdiction in which the income is allocated.
Qualifying Canadian-controlled private corporations may be eligible for a reduced federal small business rate. However, foreign-controlled corporations generally do not qualify as Canadian-controlled private corporations. International founders should not assume that the reduced small business rate will apply.
The effective tax position depends on several factors:
Businesses making taxable supplies in Canada may also need to register for the Goods and Services Tax or Harmonized Sales Tax system.
The standard GST is 5 percent, while participating provinces apply different HST rates. Some provinces maintain additional provincial sales taxes or separate administrative systems.
For many businesses, mandatory GST/HST registration begins after worldwide taxable supplies exceed the CAD 30,000 small-supplier threshold, subject to the applicable calculation periods and special rules. Voluntary registration may be possible below the threshold.
A complete tax analysis should also consider payroll deductions, customs duties, withholding tax, transfer pricing, permanent establishment exposure and sector-specific taxes.
Canada maintains a sophisticated and highly regulated financial system. Businesses can access Canadian-dollar accounts, foreign-currency facilities, domestic and international payments, merchant services, credit products and professional treasury solutions.
Nevertheless, the opening of a corporate account is not automatic. Canadian financial institutions apply detailed know-your-client, anti-money laundering and beneficial ownership procedures.
Banks may request:
Companies with foreign directors, complex ownership structures or limited Canadian activity may face additional questions. The application should present a clear commercial explanation of why the Canadian company is required and how it will operate.
Incorporation documents, banking information and tax registrations should remain consistent. Discrepancies concerning addresses, ownership or business activities can delay onboarding.
Foreign investors can generally establish and own Canadian companies, but certain investments are subject to the Investment Canada Act.
Non-Canadian investors establishing a new Canadian business or acquiring control of an existing one may need to submit a notification or application for review unless an exemption applies.
Some transactions may be assessed for their likely net benefit to Canada. Foreign investments can also be reviewed on national security grounds, regardless of value, particularly when they involve sensitive technology, critical minerals, infrastructure, personal data or strategic supply chains.
Review thresholds and filing requirements can change. They should be checked when the investment is being structured rather than assumed from previous transactions.
Additional regulation may apply in sectors such as:
Corporate registration does not replace the licences, permits or regulatory approvals required for a specific activity.
Canada has developed strong commercial ecosystems in artificial intelligence, software, cybersecurity, fintech, biotechnology, clean technology, aerospace, advanced manufacturing and digital media.
Universities, research institutions, accelerators and specialist labour markets support companies developing or commercialising intellectual property. Federal and provincial programmes may provide eligible businesses with research, development, employment or investment incentives.
The Scientific Research and Experimental Development programme is one of Canada’s best-known tax incentive frameworks. Provincial programmes may provide additional benefits.
Eligibility is fact-specific. A business should not include an incentive in its financial model until the technical activity, expenditure, ownership and documentation requirements have been reviewed.
Technology companies should also address intellectual property ownership, employee invention provisions, research agreements, data protection and transfer pricing from the beginning of operations.
A Canadian corporation should have an operational profile consistent with the functions it is expected to perform.
Relevant substance can include:
Substance does not require every company to maintain a large office. It requires the company’s legal, tax and commercial presentation to correspond with reality.
Cross-border groups must pay particular attention to payments between the Canadian company and related entities. Management fees, royalties, loans, cost-sharing arrangements and the supply of goods or services should be commercially justified and supported by transfer pricing documentation.
The company’s tax residence and permanent establishment position should also be reviewed in relation to management activity conducted outside Canada.
Canadian employment requirements are primarily governed at the provincial level, with federal rules applying to certain regulated industries.
Employers may need to address:
The company must also determine whether foreign personnel require work permits or other immigration authorisation. Ownership of a Canadian company does not itself provide employment or immigration status.
Businesses collecting personal information must consider applicable federal and provincial privacy legislation. Requirements can differ according to the province, industry and type of data processed.
Privacy policies, consent mechanisms, cybersecurity controls, international data transfers and breach-response procedures should be implemented according to the company’s actual activities.
A Canadian company must remain compliant after incorporation. The exact obligations depend on its incorporation statute, province, business activity and tax profile.
Common requirements include:
A corporate annual return is separate from the company’s tax return. Missing corporate filings can affect the company’s good standing and may eventually result in administrative dissolution.
A compliance calendar should identify each filing deadline, responsible adviser and required supporting document. This is particularly important when the directors and shareholders are located outside Canada.
Canada may be suitable for:
The jurisdiction is particularly attractive when a business intends to create genuine Canadian operations, access local customers or talent and maintain a transparent long-term corporate presence.
Companies seeking only a nominal registration without appropriate banking, management, tax and compliance arrangements may find Canada less suitable.
CFA Intelligence assists international entrepreneurs, investors and corporate groups with the planning and establishment of Canadian business structures.
Our support may include:
A Canadian company should be structured around its actual commercial purpose, ownership profile and geographic operations.
With appropriate planning, Canada can provide a credible, scalable and internationally respected platform for business across North America and global markets.
Additional perspectives on international structuring,banking, compliance and regulatory developments.