Establish a credible Scandinavian company within a transparent legal system, highly digital economy and internationally connected European market.
Denmark offers international entrepreneurs and corporate groups a combination of legal certainty, efficient digital administration, advanced infrastructure and direct access to the European market. Its strong commercial reputation makes the jurisdiction particularly relevant for businesses that value credibility, innovation and long-term operational stability. The country is not designed as a low-cost or low-tax incorporation centre. A Danish company is most effective when supported by a genuine commercial purpose, suitable management arrangements and an appropriate level of local substance. In return, the business receives access to a respected corporate framework, skilled professionals, reliable institutions and a sophisticated banking and payment environment. Denmark is suitable for technology companies, research-driven businesses, renewable energy projects, life sciences, logistics, maritime activities, manufacturing, professional services and regional headquarters. It may also serve as a platform for businesses expanding across the Nordic region and the wider European Union.
Denmark combines commercial credibility, digital administration and a highly developed innovation ecosystem.
Denmark is a member of the European Union and the European Economic Area, providing locally established companies with access to the EU single market. Danish businesses can participate in European supply chains, provide cross-border services and trade with customers throughout the region, subject to the applicable VAT, customs and industry-specific rules.
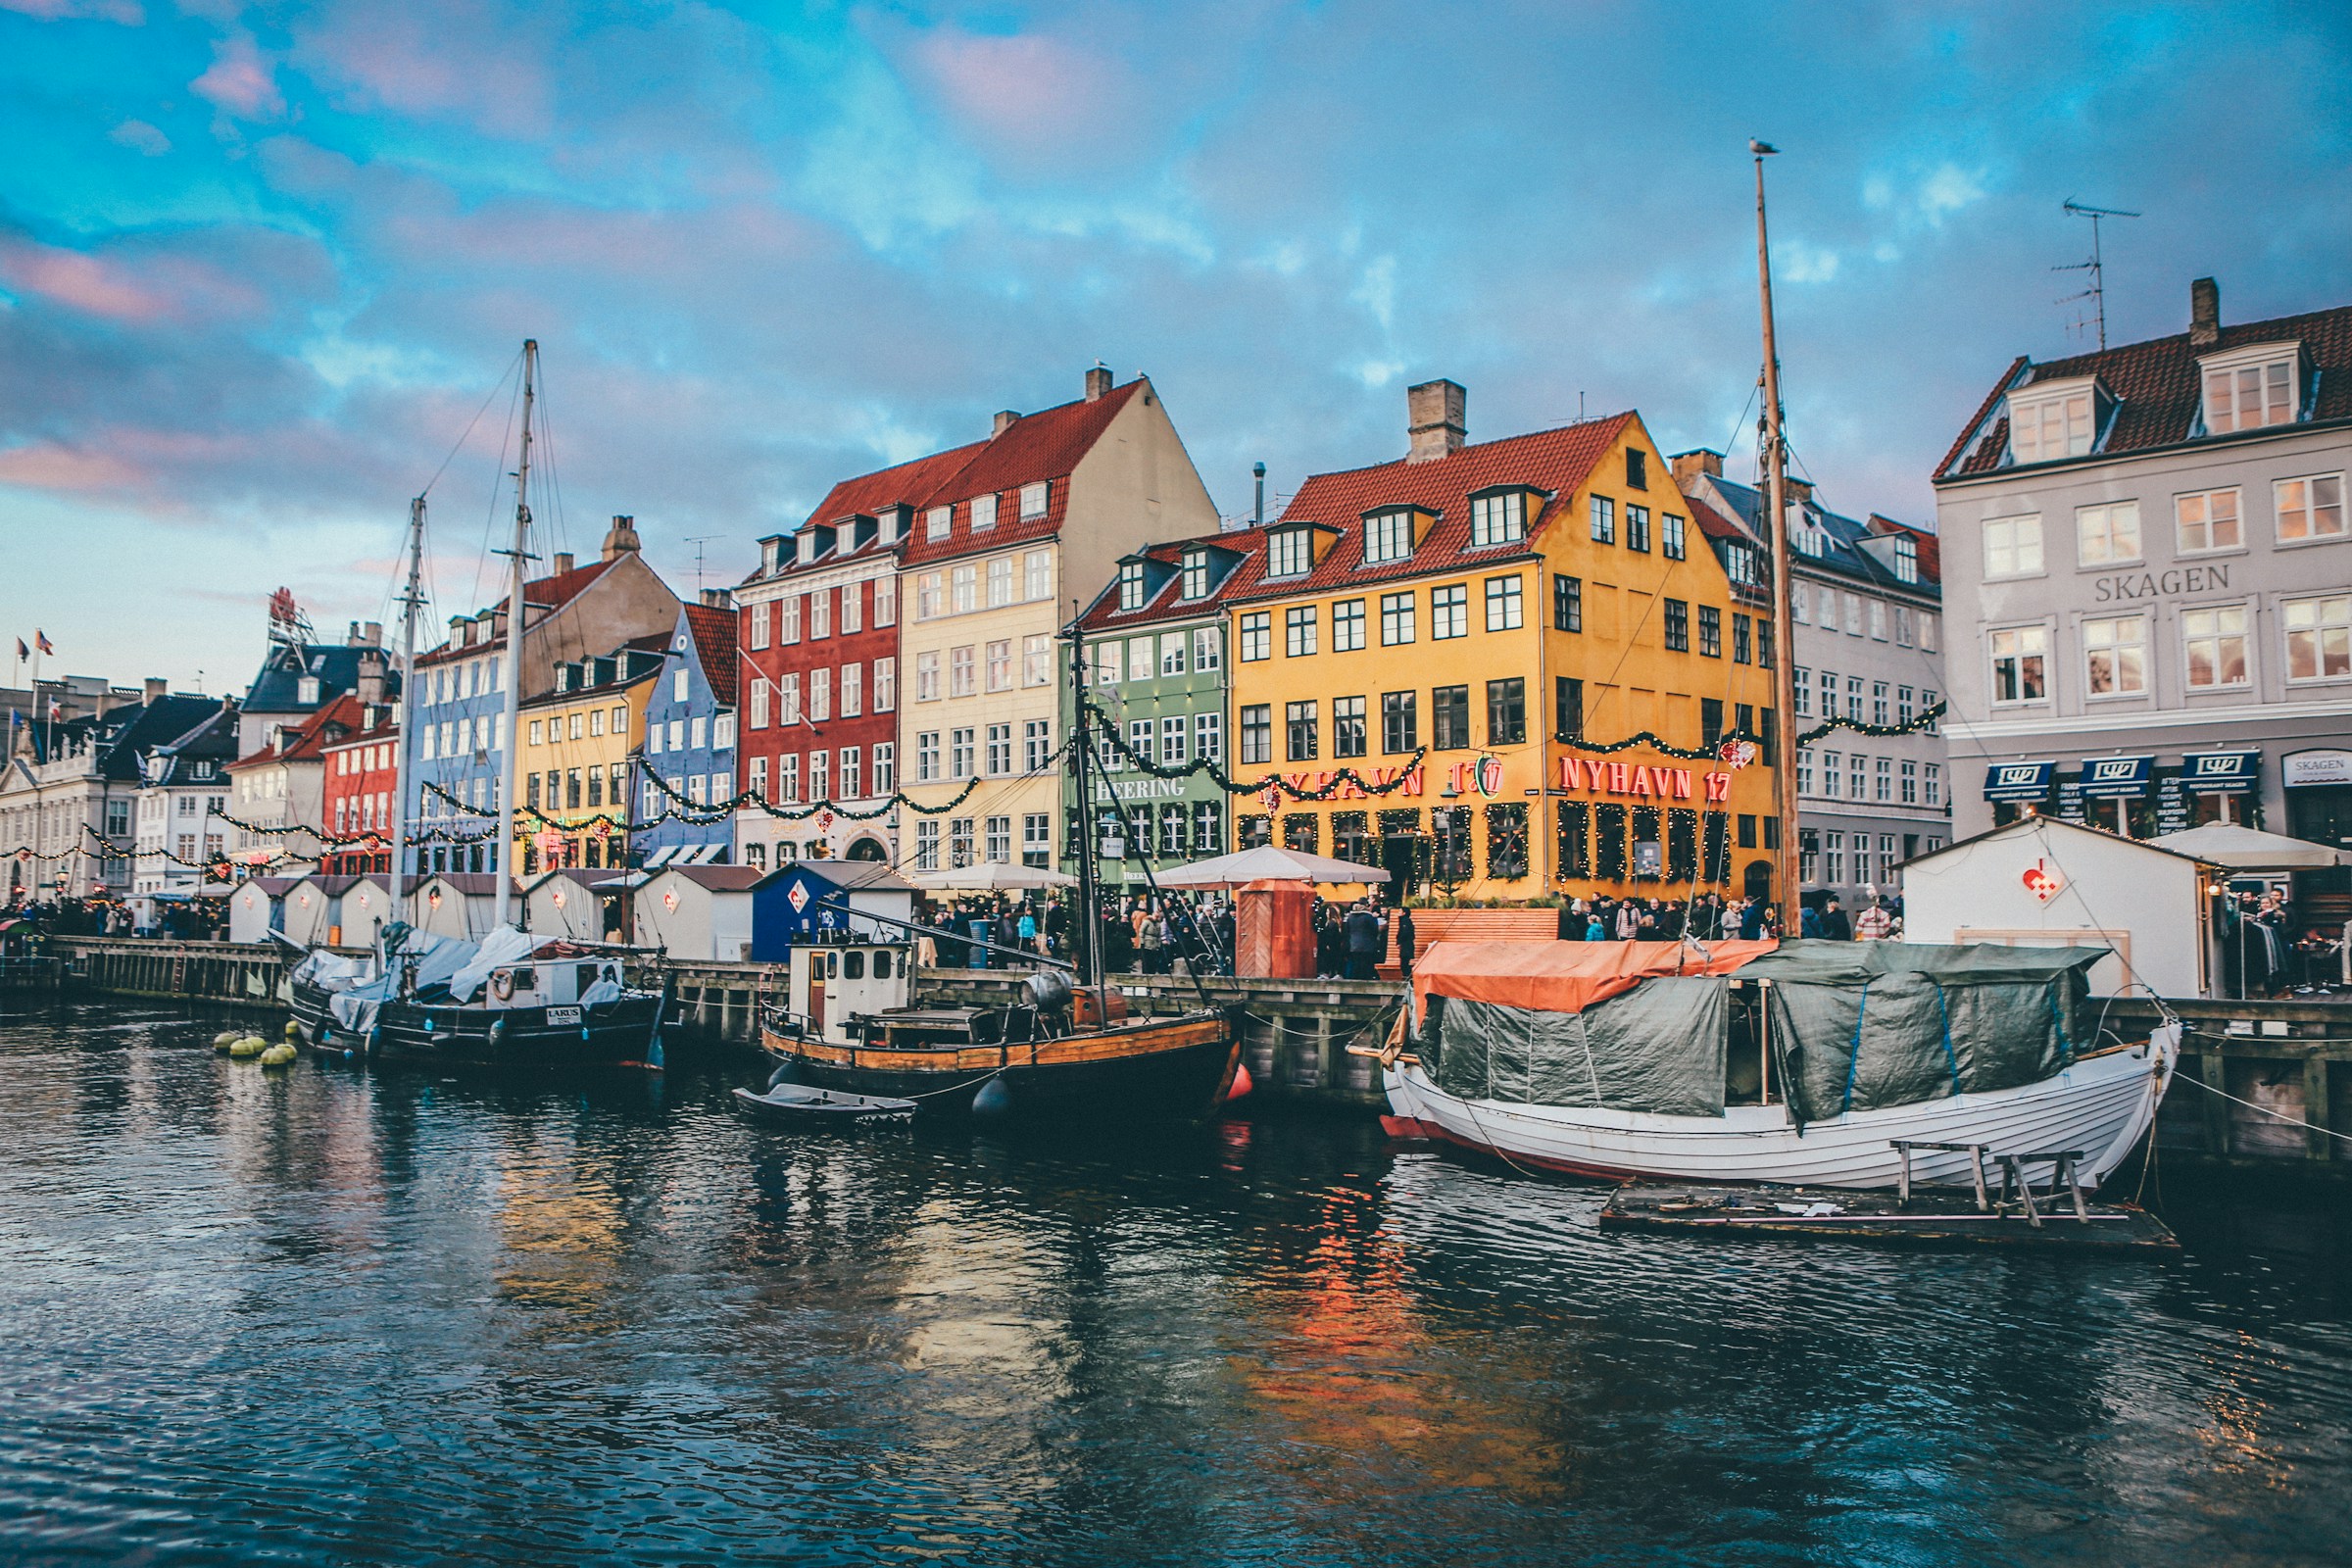
Its geographical position connects continental Europe with the Nordic countries. Modern ports, international airports, road and rail infrastructure support distribution, maritime operations and regional management activities. Copenhagen is also a recognised centre for technology, finance, life sciences, design and sustainable business.
Denmark retains the Danish krone rather than using the euro. International structures should therefore consider currency exposure when revenue, financing or operating expenses are denominated in euros, US dollars or other currencies.
The jurisdiction’s value is not limited to market access. A Danish company can strengthen commercial credibility when dealing with institutional investors, corporate customers, research partners and regulated financial institutions. However, incorporation alone does not guarantee banking access, tax advantages or operational acceptance. These outcomes depend on the quality of the underlying business model.
Foreign investors may choose from several Danish business structures. The correct form depends on ownership, capital, governance, liability, investment strategy and expected commercial activity.
The most frequently used limited liability structures are:
For most privately held international businesses, the ApS provides the most practical balance between limited liability, capital requirements and administrative flexibility.
An ApS is a separate legal entity. Its shareholders are generally liable only up to the amount invested, provided that the company is properly managed and the limited liability structure is not abused.
The minimum share capital is DKK 20,000. Capital may be contributed in cash or, subject to valuation and documentation requirements, through qualifying non-cash assets. When the company is established with only the minimum capital, the full DKK 20,000 must be paid.
An ApS may be incorporated by one or more individuals or legal entities. It can also have a single shareholder and a single member of executive management. A board of directors is generally optional unless required by the company’s articles, ownership arrangements or specific legal circumstances.
This flexibility makes the ApS appropriate for:
The company should still maintain clear decision-making procedures, ownership records and documentation of transactions involving shareholders, directors and related parties.
An A/S is generally selected for larger enterprises, businesses seeking institutional capital or organisations requiring a more formal governance model. The minimum share capital is DKK 400,000.
An A/S must maintain both executive management and a supervisory management body, such as a board of directors or supervisory board. The structure creates a clearer separation between day-to-day management and strategic oversight.
A foreign company may alternatively establish a Danish branch. The branch does not have a separate legal personality from its foreign head office, which remains responsible for its obligations. A branch can be appropriate when a corporate group wants a direct Danish presence without creating a separate subsidiary.
Before choosing a branch, the group should assess liability, taxation, financial reporting, banking and the practical availability of corporate documents from the foreign head office.
A Danish company is registered with the Danish Business Authority through the Virk business portal. Once registered, the company receives a Central Business Register number known as a CVR number.
The formation process normally requires:
Foreign founders may be able to access the registration system using an accepted foreign electronic identification method. Where direct access is impractical, a Danish professional adviser may coordinate the filing process.
Formation documents should reflect the intended ownership and governance from the beginning. Share classes, voting rights, transfer restrictions and investor protections are easier to implement during incorporation than after the company has commenced operations.
Company incorporation and operational tax registration are related but separate processes. Depending on its activities, a Danish company may need to register for VAT, payroll obligations, import or export activities and employer reporting.
The standard Danish VAT rate is 25%. Businesses supplying taxable goods or services are generally required to register when their taxable turnover exceeds DKK 50,000 over a 12-month period. Voluntary registration may be possible in certain situations.
New VAT-registered businesses are typically required to file quarterly returns during their initial operating period. Reporting frequency may later change according to turnover and the company’s filing history.
Companies with employees must register as employers and report salary, withholding tax and employment information through the relevant digital systems. Additional obligations may include holiday pay, pension contributions, occupational injury coverage and other employer-related payments.
A Danish company with a CVR number is automatically assigned Digital Post for official correspondence. Management must ensure that the mailbox is monitored because notices, deadlines and regulatory communications are generally delivered electronically.
Danish companies must maintain accurate information about their legal and beneficial owners. The ownership register should identify shareholders and relevant security interests, while beneficial ownership information must be registered with the Danish Business Authority.
A beneficial owner is normally an individual who ultimately owns or controls the company. Ownership percentages are important, but control may also arise through voting arrangements, contractual rights or other influence.
The company must keep this information current. Changes in shareholding, voting rights or ultimate control should be reviewed promptly and reported where required.
Since September 2025, beneficial ownership data is no longer generally available to the wider public through the CVR register. Access is restricted to competent authorities, regulated entities and other persons who can demonstrate a legitimate interest. The underlying obligation to identify, document and register beneficial owners remains in force.
The general Danish corporate income tax rate is 22%. A Danish resident company is normally taxed on its taxable income according to Danish tax rules, while the treatment of foreign income depends on the circumstances and applicable provisions.
International structures must also consider:
Denmark has an extensive treaty network and participates in European tax coordination mechanisms. Treaty or directive benefits are not automatic. The company must satisfy the relevant legal conditions and demonstrate that its structure reflects genuine economic activity.
Transactions between related companies should be conducted on arm’s-length terms and supported by agreements, invoices, calculations and, where necessary, transfer pricing documentation.
A Danish company should not be treated as a passive registration vehicle if strategic decisions, commercial negotiations and core operations occur elsewhere. The tax position should correspond to the company’s actual functions, assets and risks.
Danish and European banks apply detailed onboarding procedures. Registration of the company does not create an automatic right to a corporate bank account.
Financial institutions may request:
A company with a clear operational link to Denmark is generally easier to present than an entity with no local employees, premises, customers or management activity.
The banking strategy should therefore be considered before incorporation. Founders should determine which currencies, payment methods, acquiring services and cross-border transfer capabilities the company needs. Depending on the business model, a regulated European payment institution may complement a traditional bank account.
Most ordinary commercial activities do not require a general business licence. However, regulated sectors may require approval, registration or ongoing supervision before operations begin.
Additional requirements can apply to:
A regulated business should confirm its licensing position before signing contracts, marketing services or accepting customer funds. Where activities extend across the EU, the company should also assess whether a Danish authorisation can be passported or whether separate registrations are required.
Certain investments and special financial agreements may fall within Denmark’s foreign investment screening framework. The rules are particularly relevant to sensitive sectors, critical infrastructure, advanced technologies, defence-related activities, cybersecurity and strategically important resources.
Mandatory approval or notification may be required in specific circumstances. Other investments may qualify for voluntary notification where they could affect national security or public order.
Investors should conduct a screening assessment before completing an acquisition, establishing certain joint ventures or entering into agreements that provide significant influence over a Danish business.
Denmark is internationally recognised for research, digitalisation and the commercial application of new technologies. Its ecosystem includes universities, specialised research institutions, innovation clusters, established multinational companies and public funding organisations.
Important areas include:
Businesses developing innovative products may be able to access research partnerships, investment programmes or public support. Eligibility depends on the project, sector, expenditure, commercial potential and applicable state aid rules.
The presence of an innovation programme does not remove the need for sufficient financing. Applicants should normally demonstrate a credible development plan, qualified personnel and the ability to meet co-financing and reporting requirements.
Danish employment relationships are shaped by legislation, individual contracts and, in many sectors, collective bargaining agreements. Employers should prepare compliant employment terms covering salary, working hours, holidays, confidentiality, intellectual property and termination.
Payroll administration must be coordinated with tax withholding, social contributions, pension arrangements and holiday pay reporting.
Company ownership or appointment as a director does not automatically provide a foreign national with the right to live or work in Denmark. Immigration and work authorisation must be assessed separately according to nationality, role and intended activities.
Businesses processing personal data must comply with the EU General Data Protection Regulation and Danish data protection rules. This includes maintaining an appropriate legal basis, privacy notices, processor agreements, security measures and procedures for responding to data subject requests and security incidents.
A Danish company must maintain reliable accounting records and preserve supporting documents for the required period. Annual financial statements are generally prepared under Danish accounting rules and filed electronically with the Danish Business Authority.
Depending on the company’s size and classification, the annual report may be subject to audit or another form of assurance. Smaller companies may qualify for an audit exemption, provided they meet the applicable conditions.
Ongoing compliance normally includes:
A dormant company may still have reporting obligations. Failure to file accounts or maintain accurate corporate information can result in penalties and, in serious cases, compulsory dissolution.
Denmark may be particularly suitable for:
It may be less appropriate for projects focused only on minimal incorporation costs, anonymous ownership or artificial tax arrangements without genuine Danish operations.
CFA Intelligence assists international founders and corporate groups with the planning and establishment of Danish business structures.
Our support may include:
A Danish structure should be designed around the company’s commercial model rather than registration alone. CFA Intelligence coordinates the corporate, banking, tax and compliance elements required to build a practical and defensible business presence.
Additional perspectives on international structuring,banking, compliance and regulatory developments.