A holding company is often presented as the natural next step for a growing international business. Once a company enters another market, attracts investors or develops valuable assets, adding a parent entity can appear to be an obvious sign of corporate maturity. In practice, a holding structure is neither automatically necessary nor universally beneficial. It creates another legal entity, another layer of governance and additional financial, tax and reporting relationships within the group. These obligations may be justified when the holding company performs a clear ownership or investment function. Without that function, the structure can become an expensive intermediary between the shareholders and the operating business. The relevant question is therefore not whether holding companies are useful in general. It is what specific problem a holding company would solve for the organisation.
A holding company is often presented as the natural next step for a growing international business. Once a company enters another market, attracts investors or develops valuable assets, adding a parent entity can appear to be an obvious sign of corporate maturity. In practice, a holding structure is neither automatically necessary nor universally beneficial. It creates another legal entity, another layer of governance and additional financial, tax and reporting relationships within the group. These obligations may be justified when the holding company performs a clear ownership or investment function. Without that function, the structure can become an expensive intermediary between the shareholders and the operating business. The relevant question is therefore not whether holding companies are useful in general. It is what specific problem a holding company would solve for the organisation.
A holding company primarily owns shares in other companies. It may also exercise shareholder rights, appoint directors, approve major investments and coordinate capital allocation across the group.
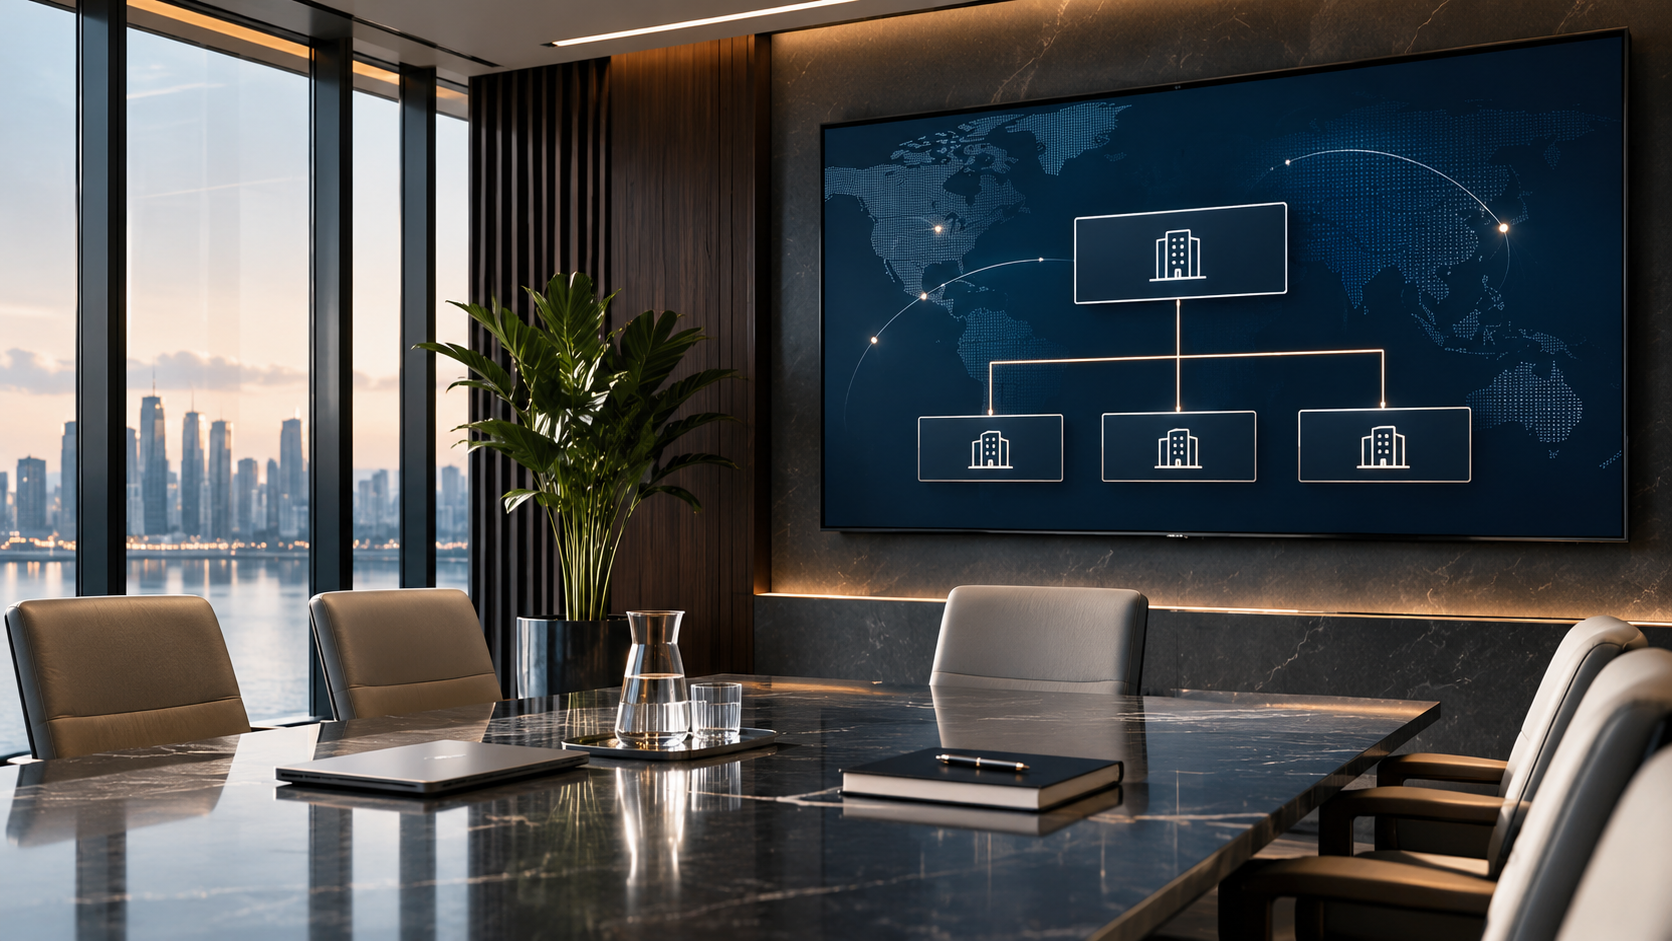
Its role differs from that of an operating company. An operating entity sells products or services, enters into customer contracts, employs personnel and manages daily commercial risk. A holding company normally sits above these activities and provides a common ownership framework for one or more subsidiaries.
Depending on the structure, the parent may receive dividends, provide capital to subsidiaries, make acquisitions or hold certain long-term investments. Some holding companies also perform genuine management or treasury functions, although these activities require appropriate personnel, documentation and substance.
The case for a holding company usually becomes stronger when ownership is more complex than the operation of a single business.
For example, a group may have subsidiaries serving different countries, products or regulated markets. A parent entity can provide one ownership point above those businesses while allowing each operating company to maintain its own contracts, employees and local responsibilities.
A holding company may also be useful when investors are expected to participate in the wider group rather than in one subsidiary. Instead of negotiating separate interests in several operating companies, investors can acquire shares at parent level, subject to one shareholder agreement and one governance framework.
Acquisitions create another potential use. A group planning to purchase and develop additional businesses may use a holding company to coordinate ownership and financing while preserving the legal identity of each acquired operation. Similarly, founders considering succession or a future group-level sale may benefit from having ownership organised through one parent entity.
These are identifiable corporate objectives. “International growth” on its own is not.
A business with one operating company, one principal market and no immediate investment or acquisition plans may gain little from adding a parent entity.
The holding company would still require incorporation, accounting, corporate maintenance and potentially a separate bank account. Transactions between the two companies would need to be documented, and the group could face additional reporting or consolidation requirements. Transferring the existing business into the new structure may itself have legal and tax consequences.
A holding company should not be introduced solely because the founders would like the organisation to appear more international. Nor should it be assumed that a parent company will improve banking access. Financial institutions may instead request additional information about the complete ownership chain, the source of wealth used to establish the group and the commercial purpose of payments between the entities.
If the additional layer cannot be explained to a bank, investor, tax authority or business partner in a few clear sentences, its purpose may not yet be sufficiently developed.
Once the commercial need for a holding company has been established, the next question is where it should be located.
Taxation is a legitimate part of this analysis, but it cannot be considered in isolation. Relevant factors may include the treatment of dividends and capital gains, withholding taxes, access to applicable treaty benefits, corporate-law flexibility and the rules governing distributions, share transfers and investor protection.
The analysis should also consider controlled foreign company rules, anti-abuse provisions, beneficial ownership requirements and the tax position of the ultimate shareholders. A structure that appears efficient from the perspective of the holding company may produce an entirely different outcome for a founder or investor resident elsewhere.
Non-tax considerations are equally important. Investors may prefer a familiar legal system. A regulated group may need its ownership structure to meet supervisory requirements. The jurisdiction must also be workable for banking, governance and the level of physical or managerial substance the company can realistically maintain.
There is therefore no universally “best” holding jurisdiction. The appropriate location depends on the subsidiaries, shareholders, capital flows and long-term plans of the particular group.
Placing several subsidiaries beneath one parent company creates an organisation chart. Governance determines whether that organisation can actually function.
The group should define which decisions remain with subsidiary management and which require parent or shareholder approval. Day-to-day contracts, staffing and customer matters may belong to the operating entities, while acquisitions, major borrowing, dividend distributions and changes in business strategy may be reserved for the holding company or its shareholders.
Where several founders or investors are involved, the shareholder agreement should address voting rights, board appointments, funding obligations, share transfers, deadlock and exit arrangements. The constitutional documents and board procedures must then support those agreements.
Financial reporting is another essential component. A parent company cannot oversee a group effectively if it receives inconsistent or incomplete information from its subsidiaries. Management accounts, budgets, compliance reporting and material-risk notifications should follow an agreed process across the organisation.
Without these mechanisms, the holding company owns the subsidiaries legally but contributes little to their governance.
A holding structure creates financial relationships between entities that previously may not have existed.
Subsidiaries may distribute dividends to the parent. The holding company may provide new equity, issue intercompany loans or fund an acquisition. If it supplies genuine management, administrative, treasury or intellectual-property services, it may also receive payments under appropriate intercompany agreements.
Each flow has a different legal, accounting and tax character. Dividends are not interchangeable with service fees, and shareholder funding is not the same as commercial revenue. The transactions must be correctly approved, recorded and supported by the relevant agreements.
Transfer-pricing and withholding-tax considerations may apply, while regulated subsidiaries can face additional restrictions on distributions or related-party transactions. The holding company should also have sufficient financial records to explain where funds originate and why they are moving between particular entities.
Using the parent as a general account through which unrelated group payments pass can weaken rather than strengthen the structure.
A holding company does not automatically receive easier access to banking because it owns several businesses.
During onboarding, a financial institution may examine the ultimate beneficial owners, the source of the capital used to establish or acquire the subsidiaries and the activities conducted throughout the group. It may also request corporate charts, financial statements, dividend documentation, intercompany agreements and evidence supporting the commercial purpose of the parent.
A pure holding company can sometimes require more explanation because it has no ordinary customer revenue. The bank needs to understand whether incoming funds will consist of shareholder capital, dividends, investment proceeds or intercompany repayments, and where outgoing payments will be directed.
Transparent ownership and proper documentation help this process, but they do not remove the bank’s independent risk assessment. Banking should therefore be tested as part of the structure’s feasibility rather than presented as an automatic benefit of creating a holding company.
Consider two founders who initially own one operating company directly. The business later establishes subsidiaries in two additional markets and begins preparing for external investment.
If the investor is expected to participate in the entire business, maintaining separate direct ownership in all three operating companies may complicate the transaction. A parent company could provide one equity entry point. The founders would hold shares in the parent, the parent would own the operating subsidiaries and the investor could subscribe at group level.
The structure could also establish group-wide reserved matters, consolidated reporting and a common framework for future acquisitions.
Implementing it, however, is not simply a matter of registering another company. Transferring the existing shares may trigger consent requirements, valuation questions and tax consequences. Banking and licensing arrangements may need to be updated, and the subsidiaries must document their future relationships with the parent.
The holding company is useful in this example because it solves a defined ownership and investment problem — not merely because the group operates internationally.
Before establishing a holding company, the shareholders should be able to answer several practical questions:
A clear answer does not guarantee that one particular structure is correct, but it establishes whether a holding company has a genuine commercial role.
Holding structures can support investment, governance, acquisitions and international expansion. They can also create unnecessary cost and complexity when introduced too early or designed around taxation alone. The strongest structure is therefore not the one with the greatest number of entities. It is the one in which every entity performs a function the business can explain, document and maintain.
Additional perspectives on international structuring,banking, compliance and regulatory developments.