Ireland has developed into one of Europe’s most established locations for internationally active companies, combining access to the European Union, an English-speaking legal and commercial environment, a skilled workforce and mature technology, life sciences and financial services ecosystems. Its value extends beyond a competitive tax framework to the ability to build substantial operations within a credible and internationally recognised European jurisdiction.
Ireland occupies a distinctive position within the European business landscape. It is an EU and euro-area jurisdiction with an English-speaking commercial environment, a common-law legal tradition and a long record of attracting international investment. Its corporate ecosystem supports companies across technology, software, financial services, pharmaceuticals, medical technology, advanced manufacturing and internationally traded services. This concentration of industries has created experienced professional networks, specialised talent and an operating environment familiar with complex cross-border business models. Ireland should not, however, be selected solely because of its headline corporate tax rate. The jurisdiction increasingly rewards companies that conduct genuine trading activity, employ qualified personnel, manage intellectual property responsibly and maintain real decision-making functions within the country. For international groups, Ireland is strongest when it serves a defined operational purpose: developing technology, managing European customers, conducting research, manufacturing products, holding regulated permissions or coordinating substantive regional activities.
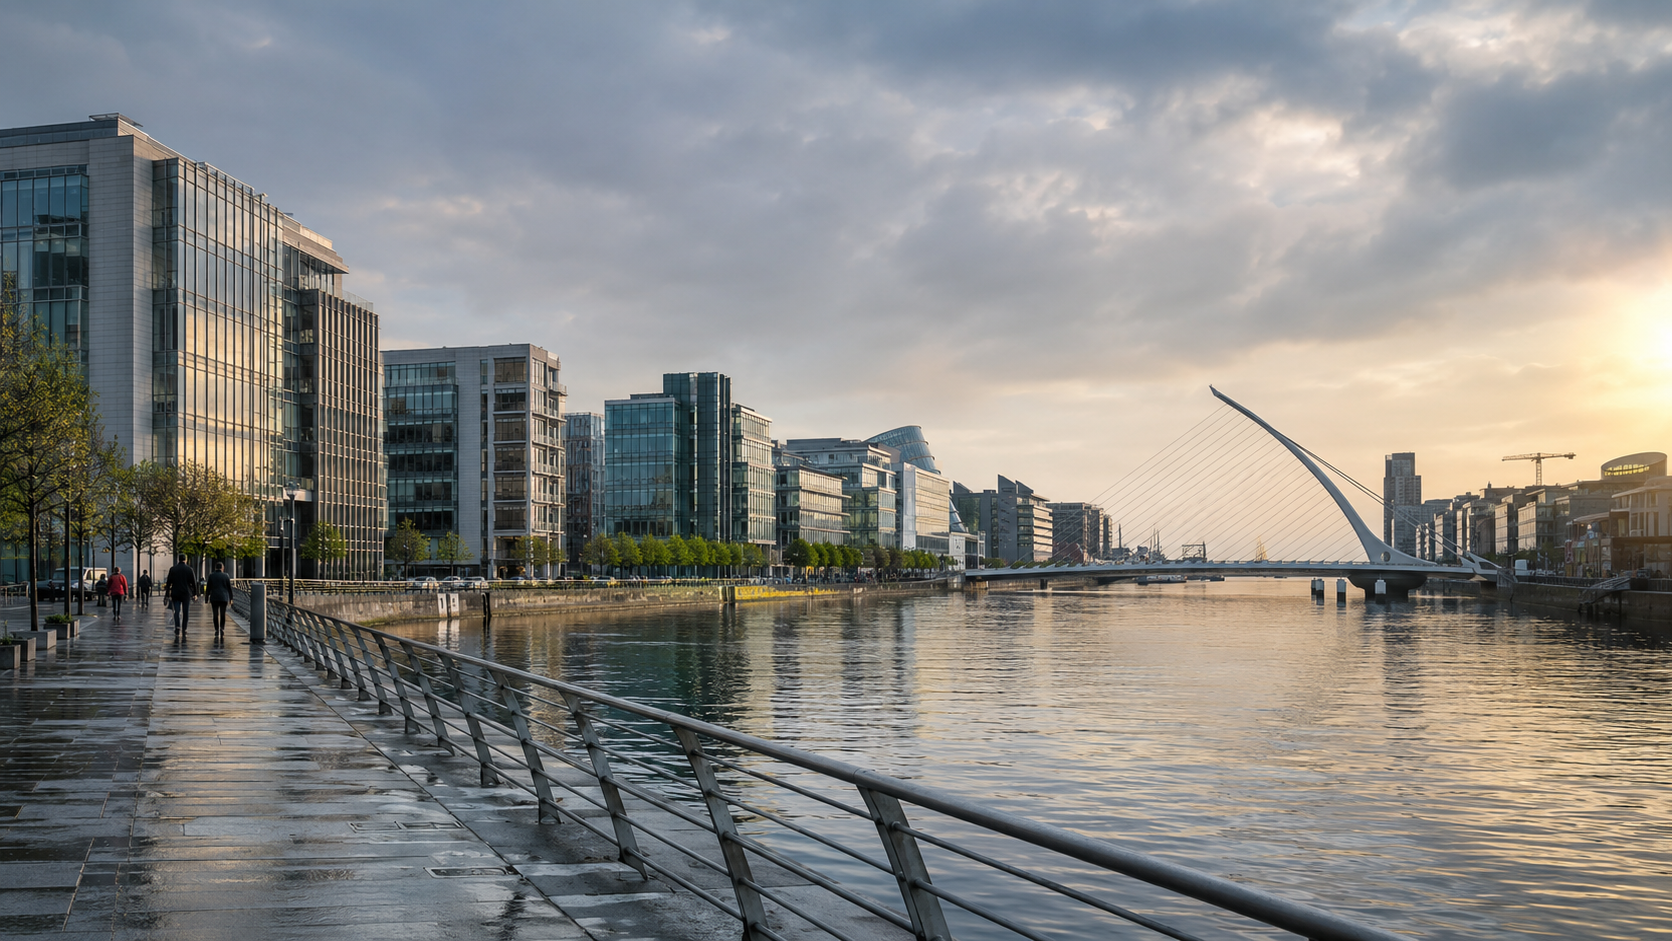
Ireland combines European market access with a mature environment for technology, innovation and internationally traded business.
The most common structure for privately owned businesses is the private company limited by shares, generally referred to as an LTD. It provides limited liability and a flexible governance framework suitable for operating companies, subsidiaries and many founder-led businesses.
An LTD may have a single director, but where only one director is appointed, the company secretary must be a separate person. Other Irish company forms generally require at least two directors. Directors must be individuals rather than corporate entities and are subject to statutory duties under Irish company law.
At least one director is generally required to reside within the European Economic Area. A company without an EEA-resident director may instead use a prescribed bond with a value of €25,000. Following incorporation, an exemption may also be available where the company demonstrates a real and continuous link with economic activities carried on in Ireland.
Every company must maintain a physical registered office within the State. This address is used for formal notices and must be more than a post office box. The company must also appoint a secretary, maintain statutory registers and keep adequate accounting records.
The Companies Registration Office provides the official requirements governing directors, secretaries, EEA residence and the available exemptions.
Company incorporation is completed through the Companies Registration Office. The application identifies the proposed name, registered office, directors, secretary, shareholders, share structure and intended business activity.
Incorporation does not complete the company’s wider establishment. The business may also need to register with Revenue for corporation tax, payroll taxes and VAT, depending on its activities. Employers must implement Irish payroll and employment procedures, while regulated businesses may require separate authorisation before commencing operations.
Irish companies are required to maintain an internal record of their beneficial owners and submit the relevant information to the Central Register of Beneficial Ownership. The RBO acts as the statutory repository for information concerning the natural persons who ultimately own or control Irish corporate entities.
Annual returns must be filed with the CRO, generally together with the required financial statements. Audit exemptions may be available to qualifying companies, but they depend on meeting the relevant statutory conditions and filing deadlines.
A company that fails to maintain its statutory records or submit returns on time may lose exemptions and expose the company and its officers to penalties. Ongoing governance should therefore be planned from the beginning rather than treated as a year-end administrative exercise.
Ireland gives companies access to the European Union’s single market and its legal framework for the movement of goods, services, capital and people. This can make it attractive for companies developing European customer relationships or establishing an operational base within the EU.
Its continued membership of both the EU and the euro area is particularly relevant for businesses seeking an English-speaking European location after the United Kingdom’s withdrawal from the Union. Ireland can support euro-denominated contracts, EU employment structures and commercial relationships with customers throughout the European Economic Area.
EU establishment does not mean that every service can automatically be offered throughout Europe. Financial services, payments, insurance, healthcare, telecommunications and other regulated sectors may require specific authorisation or notification procedures.
VAT registrations, consumer protection, data protection, product standards and local permanent establishment rules must also be considered when the company operates in several European countries. Ireland provides access to the European framework, but the company must still understand how that framework applies to its particular industry.
Ireland’s strongest proposition is the depth of its operating ecosystem. The country has attracted sustained investment in software, cloud services, cybersecurity, semiconductors, pharmaceuticals, biotechnology, medical technology, financial services and advanced manufacturing.
This creates benefits that go beyond the presence of individual multinational companies. Specialist advisers, research institutions, experienced managers and technically qualified employees have developed around these industries. International businesses can therefore access an environment already accustomed to product development, regulated manufacturing, intellectual property management and complex European operations.
Ireland’s life sciences sector includes pharmaceutical, biopharmaceutical and medical technology activities, while its technology base supports software engineering, digital platforms, cloud infrastructure and emerging AI applications. IDA Ireland identifies technology, life sciences, engineering and international financial services among the country’s central investment sectors.
The jurisdiction can also support smaller international companies, particularly where they require an English-speaking EU base and intend to recruit, develop technology or work directly with European customers. The commercial case is strongest where the Irish entity performs meaningful functions rather than merely holding contracts created and managed elsewhere.
Ireland operates within the euro area and provides access to domestic banks, international financial institutions, payment companies and fintech providers. This can support euro payments, payroll, customer collections and financial operations across the European Union.
Opening a corporate account is nevertheless a separate process from company incorporation. Banks and payment institutions evaluate the ownership structure, directors, activities, source of funds, expected transactions and countries involved. They may also consider whether the business has a credible connection to Ireland.
A newly incorporated company with no local management, employees, premises or customers may find the banking review more difficult than an operational business with a clearly documented Irish purpose. Contracts, financial projections, websites, shareholder information and evidence of commercial activity should present a consistent business profile.
International groups should determine whether the Irish entity requires a local operating account, multicurrency facilities, merchant acquiring, safeguarding arrangements or access to particular payment rails. This analysis should be completed before the company’s contractual and invoicing structure is finalised.
Ireland applies a 12.5% corporation tax rate to qualifying trading income. A 25% rate applies to non-trading income, including many forms of investment and rental income, as well as income from certain excepted trades. The distinction between trading and passive income is therefore fundamental.
A company incorporated in Ireland on or after 1 January 2015 is generally treated as Irish tax resident unless it is regarded as resident in another jurisdiction under an applicable double taxation agreement. Incorporation should consequently be assessed together with management, control and treaty considerations.
The international tax environment has also changed Ireland’s corporate framework. The Pillar Two rules provide for a minimum effective tax rate of 15% for multinational and large domestic groups within scope, generally those meeting the €750 million consolidated revenue threshold. Ireland has implemented the Income Inclusion Rule, Undertaxed Profits Rule and a domestic top-up tax within its legislation. Irish Revenue provides the current framework.
Ireland also maintains an extensive network of double taxation agreements and has introduced mechanisms relevant to foreign dividends, group structures and cross-border investment. Treaty benefits and exemptions are subject to conditions and should not be assumed solely because a company is incorporated in Ireland.
The official corporation tax rates and distinction between trading and non-trading income are published by Irish Revenue.
Ireland’s tax framework includes support for companies conducting qualifying research and development. The R&D Corporation Tax Credit is designed to encourage substantive scientific and technological activity carried out by companies within the Irish tax system.
The credit was increased from 30% to 35% under Finance Act 2025. Under the current timing rules, the 35% rate generally applies to accounting periods ending on 31 December 2026 or later. Eligibility depends on the nature of the activity and expenditure, and claims must satisfy the applicable scientific, documentary and filing requirements.
The credit should not be treated as an automatic benefit for companies describing themselves as innovative. A business must demonstrate qualifying scientific or technological advancement, maintain technical records and connect the claimed expenditure with eligible activities.
Ireland also provides a framework for intellectual property acquisition, development and exploitation. The appropriate treatment depends on ownership, functions, development activity, transfer pricing and the relationship between the Irish company and other members of the group.
A company holding valuable intellectual property without personnel, decision-making or relevant development functions may face challenges under modern substance and international tax principles. The legal ownership of IP should correspond with the people, risks and activities that create and manage its value.
Ireland’s standard VAT rate is 23%, although reduced rates and exemptions apply to particular goods and services. The correct treatment depends on the nature of the supply, the customer’s status and location, and whether the transaction involves goods, services, imports or exports.
Companies providing services to business customers in other EU member states may need to apply the reverse-charge mechanism, verify customer VAT numbers and submit the relevant reporting. Sales to consumers can create different obligations, particularly for digital services and cross-border e-commerce.
Businesses moving goods through Ireland must consider customs, import VAT, warehousing and supply-chain arrangements. Northern Ireland also has particular relevance for goods moving between the United Kingdom, Ireland and the wider European Union.
VAT should therefore be integrated into the company’s commercial model. The place where contracts are signed or invoices are issued does not by itself determine the treatment of every transaction.
Ireland provides a mature regulatory environment, but this also creates significant compliance responsibilities. Companies must maintain accurate corporate records, financial statements, beneficial ownership information and tax filings.
Financial services, payment institutions, electronic money businesses, investment firms, insurance companies and certain virtual asset service providers may fall within the supervision of the Central Bank of Ireland. Establishing a company is not equivalent to receiving permission to conduct a regulated activity.
Ireland’s position within the EU means that companies must also consider European data protection, consumer protection, employment and competition requirements. For digital businesses, GDPR compliance and the location of data-processing activities can form an important part of the operating structure.
Directors are expected to understand the company’s affairs and exercise genuine oversight. Using nominal officers without meaningful involvement can create governance, banking and tax risks. Board decisions, financial control and commercial strategy should reflect the functions attributed to the Irish company.
Ireland is most effective for companies prepared to establish a genuine operating presence. Substance may include locally based directors, qualified employees, appropriate premises, active bank accounts, accounting functions and evidence that important decisions are made in Ireland.
The necessary level of substance depends on the business. A software company may require developers and commercial management, while a regional headquarters may need senior decision-makers, finance personnel and authority over European operations. A manufacturing or life sciences company will require considerably more extensive facilities and operational infrastructure.
Substance must also be considered across the wider group. Contracts, transfer pricing and the allocation of income should correspond with the functions, assets and risks of each company. An Irish entity should not receive significant profits if the activities generating those profits are performed entirely elsewhere without appropriate arrangements.
A well-designed operating presence supports banking, tax residence, treaty access and relationships with employees, customers and regulators. It also makes the company more resilient as international transparency standards continue to develop.
Ireland may be appropriate for technology, life sciences, internationally traded services, financial services and other companies seeking a substantive European base. It can also support groups that value an English-speaking EU environment, access to skilled talent and a legal system familiar to international investors.
It may be less suitable where the proposed company would have no employees, management or commercial activity in Ireland. The cost of qualified personnel, premises, professional services and continuing compliance should be compared with the actual strategic benefit of the jurisdiction.
Ireland is also not a universal 12.5% structure. The applicable tax treatment depends on whether income is trading or passive, whether the company belongs to a Pillar Two group and how its activities interact with international tax and transfer pricing rules.
The correct question is not whether Ireland offers a competitive headline rate. It is whether the company can establish an economically credible Irish operation capable of supporting its European and international objectives.
Ireland’s position as a leading European business jurisdiction is based on more than taxation. Its value comes from the combination of EU market access, legal credibility, industry expertise, international talent and an established environment for innovation and investment.
The strongest Irish structures align corporate ownership with real functions. Management, employees, research, intellectual property, contracts and financial flows should form part of a coherent operating model.
When these elements are properly designed, Ireland can provide a durable platform for European business, technological development and international growth. The objective should not be simply to register an Irish company, but to build an operation capable of performing a meaningful role within the wider group.
Additional perspectives on international structuring,banking, compliance and regulatory developments.