Mauritius combines a competitive tax framework with political stability, established financial regulation and access to markets across Africa, Asia and the Indian Ocean. For international businesses, its value extends beyond taxation: the jurisdiction can support cross-border investment, regional headquarters, fund structures, professional services and internationally managed commercial operations.
Mauritius has developed from a small island economy into a recognised international financial and business centre. Its legal system draws on both common law and civil law principles, English and French are widely used in professional environments, and its financial sector serves companies and investors operating across several regions. The country is frequently associated with tax efficiency, but the modern Mauritian framework is built around transparency, regulation and economic substance. Preferential treatment is not available simply because a company has been incorporated on the island. Tax residence, qualifying income, local management, operational expenditure and core income-generating activities must be considered together. This distinction is essential. Mauritius can be highly effective for businesses with credible international activities and a clear reason for using the jurisdiction. It is considerably less suitable for structures created only to obtain a low tax rate without corresponding management, governance or commercial substance.
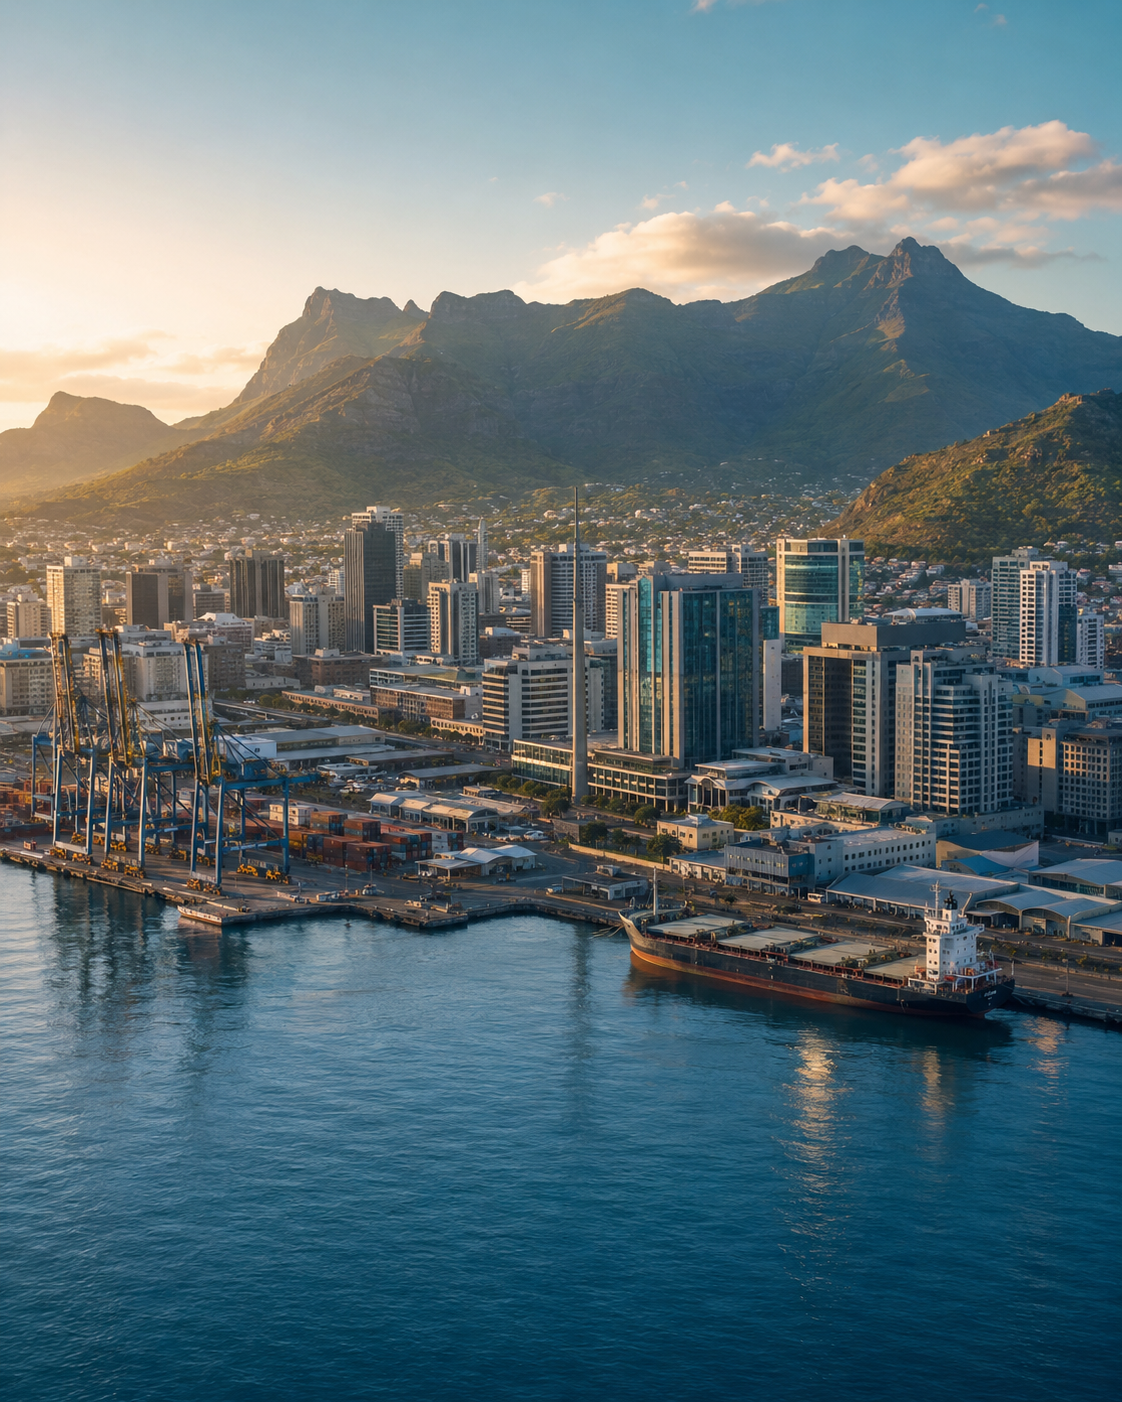
Mauritius offers a combination of commercial, regulatory and tax characteristics that can support carefully structured international operations.
The standard corporate income tax rate in Mauritius is 15 percent. Companies engaged in qualifying exports of goods may be taxed at 3 percent, while partial exemptions may apply to specified categories of income and licensed activities.
These rates make Mauritius competitive, but they do not tell the full story. Eligibility for a partial exemption depends on the nature of the income and the company’s ability to satisfy defined substance conditions. The company must conduct its core income-generating activities in Mauritius, maintain an adequate level of qualified personnel and incur expenditure proportionate to its operations.
Certain larger companies may also be subject to the temporary Fair Share Contribution applying to income derived between 1 July 2025 and 30 June 2028. Companies meeting the relevant turnover and chargeable income thresholds may face an additional contribution of 5 percent where their ordinary income tax rate is 15 percent, or 2 percent where the applicable rate is 3 percent.
This means that Mauritius should not be evaluated solely through an advertised headline rate. The effective tax position must be calculated by reference to the company’s income profile, scale, available exemptions, operating expenditure and any additional contributions that may apply.
An ordinary domestic company may be suitable where the business will operate primarily within Mauritius. International structures, however, often require either a Global Business Licence or Authorised Company status.
A company holding a Global Business Licence is generally used where the business is conducted principally outside Mauritius but the company is centrally managed and controlled from within the jurisdiction. It is treated as a Mauritian resident company and may potentially benefit from the country’s tax treaty network, subject to the relevant treaty, tax residence and anti-abuse conditions.
A Global Business Licence does not convert a nominal company into a tax-resident business. The structure must demonstrate meaningful Mauritian management. This normally requires local governance, properly conducted board meetings, maintained records, an appropriate bank account and sufficient substance for the company’s activities.
An Authorised Company is different. It is generally used where the majority of shares or voting rights are held by non-citizens, the company conducts business principally outside Mauritius and its central management and control remain outside the country. It is therefore treated as non-resident for Mauritian tax purposes and does not ordinarily receive access to Mauritius tax treaties.
The Authorised Company can be appropriate for certain international trading, consulting or holding activities, but it should not be presented as a substitute for a tax-resident Global Business structure. The two vehicles serve different purposes and produce materially different tax, governance and treaty outcomes.
Global Business and Authorised Company applications are handled through a licensed Mauritian management company. The management company assists with incorporation, regulatory submissions, administration, compliance and communication with the Financial Services Commission.
Mauritius applies partial exemptions of 80 or 95 percent to specified forms of income and activities when the statutory conditions are met.
Depending on the circumstances, eligible categories may include certain foreign dividends, interest income, profits attributable to a foreign permanent establishment, income derived by qualifying collective investment schemes and income from specified financial, aviation, maritime or technology-related activities.
The exemption applies to qualifying income, not automatically to every form of revenue earned by the company. A mixed business may therefore have several categories of income receiving different treatment.
A company should determine where its revenue originates, which entity performs the underlying functions, where decisions are made and which expenses support the income. This analysis is especially important for holding companies, treasury structures, investment managers and businesses receiving cross-border service fees.
Mauritius also applies VAT at a standard rate of 15 percent. VAT registration and reporting may be required where taxable activities are conducted in Mauritius or applicable registration thresholds are reached. Companies supplying digital or electronic services into Mauritius must also consider rules applying to foreign suppliers.
Tax planning should therefore begin with transaction flows rather than the corporate rate. Dividends, interest, royalties, management fees, capital gains, related-party financing and distributions to shareholders may all produce different consequences in Mauritius and in the countries where counterparties or owners are located.
Mauritius maintains double taxation agreements with jurisdictions across Africa, Europe, Asia and the Middle East. This network has contributed significantly to its development as a platform for regional investment and cross-border business.
A treaty may reduce withholding taxes, define the allocation of taxing rights and provide mechanisms for resolving situations where two jurisdictions seek to tax the same income. For investors entering African or Asian markets, this can create greater legal and financial predictability.
Treaty benefits are not automatic. The company must qualify as a Mauritian tax resident under domestic law and the relevant agreement. It may also need to demonstrate beneficial ownership, commercial substance and a business purpose consistent with the arrangement.
Modern treaties increasingly contain principal purpose tests and other anti-abuse provisions. A structure created mainly to obtain treaty benefits may therefore be challenged even if the company has completed the formal incorporation process.
The analysis must also account for changes to individual treaties. Agreements may be amended, renegotiated or terminated, while source countries can introduce domestic anti-avoidance measures that affect the expected result.
A Mauritius structure should consequently remain commercially viable even if a particular treaty advantage becomes less favourable in the future.
Mauritius is strategically positioned in the Indian Ocean and has developed trade and investment relationships extending across Africa and Asia.
The country participates in African regional frameworks and maintains agreements intended to support access to major international markets. These include its arrangements with the European Union, participation in African trade structures, the Mauritius-China Free Trade Agreement and the Comprehensive Economic Cooperation and Partnership Agreement with India.
This positioning can be valuable for investment platforms, regional headquarters, professional services, fund management, technology businesses and companies coordinating activities across several African jurisdictions.
Mauritius also offers multilingual professional expertise and a time zone that overlaps with working hours in Asia, the Middle East, Africa and Europe. These factors can support real management functions rather than purely formal corporate administration.
However, Mauritius is a comparatively small domestic market. Businesses using the jurisdiction generally need a clear international or regional strategy. A company established without defined target markets, counterparties or operational functions may struggle to justify its commercial purpose to banks, regulators and tax authorities.
Mauritius has a developed banking sector with domestic and international institutions offering corporate accounts, foreign currency facilities, trade finance and investment-related services.
Account opening remains separate from company incorporation and regulatory approval. Neither a certificate of incorporation nor a Global Business Licence guarantees that a bank will accept the company.
Banks assess the complete risk profile of the proposed relationship. This includes ultimate beneficial ownership, source of funds, source of wealth, expected turnover, transaction currencies, countries of operation, customer and supplier profiles, business experience and the economic purpose of the structure.
Companies operating in regulated industries, digital assets, high-risk markets or complex cross-border payment chains may face enhanced due diligence or limited banking options. Recently incorporated companies may also be asked to provide business plans, agreements, financial projections and evidence of intended activity.
A credible application should clearly explain why Mauritius has been selected, how the company will generate income and how expected payments correspond with its stated business model.
Banking strategy should therefore be planned before the company is incorporated. The selection of legal form, licence, management arrangements and substance can materially affect account-opening feasibility.
Substance in Mauritius is not a standard package that can be satisfied through a registered address and occasional signatures.
The required level depends on the company’s functions and income. A holding company, investment manager, regional headquarters, financing vehicle and international trading business will each require a different operational profile.
For a Global Business company, management and control should be exercised from Mauritius in a manner consistent with its claimed tax residence. Directors must understand the company’s activities, evaluate decisions and maintain evidence that their authority is genuine.
Board meetings should address real commercial matters. Contracts, investments, financing and distributions should be considered and approved through documented governance processes. The company should maintain sufficient records and resources to support the functions attributed to it.
Where employees, office facilities or specialist expertise are required, the level of expenditure should be proportionate to the business. Outsourcing may support certain functions, but it should not leave the company without meaningful oversight or decision-making capacity.
The objective is not to create artificial indicators of presence. It is to establish a structure whose management, resources and financial flows can be explained consistently to the Financial Services Commission, Mauritius Revenue Authority, banks and foreign tax authorities.
The Financial Services Commission regulates the non-bank financial services sector and global business in Mauritius. Companies carrying out regulated activities must obtain the appropriate licence before beginning operations.
Investment management, fund administration, securities activity, insurance, payment intermediary services, virtual asset services and other financial businesses may involve specific capital, governance, staffing and compliance requirements.
A Global Business Licence alone does not authorise regulated financial services. The company may require an additional licence corresponding to its exact activity.
Applicants should assess regulation before finalising the corporate structure. The Financial Services Commission may evaluate controllers, beneficial owners, directors, business plans, financial resources, internal controls and the competence of key personnel.
Licensed entities must also maintain ongoing compliance with anti-money laundering, counter-terrorist financing, reporting and governance obligations. A structure that appears workable at incorporation may become commercially impractical if the cost and complexity of maintaining the required regulatory framework have not been modelled.
A Mauritius company must maintain proper corporate and accounting records, submit annual filings and comply with beneficial ownership disclosure requirements.
Depending on its classification, the company may need audited financial statements, annual tax returns, regulatory submissions and periodic reporting through its management company. Changes to directors, shareholders, beneficial owners or business activities may require notification or prior approval.
Transactions with shareholders and related companies should be conducted on commercially supportable terms. Service agreements, loans, intellectual property arrangements and management fees must reflect genuine activity and should be supported by appropriate documentation.
Compliance must also extend beyond Mauritius. The company’s shareholders, directors and counterparties may have reporting obligations in their own jurisdictions. Controlled foreign company rules, permanent establishment exposure, transfer pricing and tax residence tests can affect the overall structure even where the Mauritius entity is fully compliant locally.
The company should therefore be reviewed as part of an international architecture rather than as an isolated vehicle.
Mauritius may be unsuitable for founders seeking an anonymous company, guaranteed banking or an arrangement without meaningful reporting and substance.
It may also be inefficient where all shareholders, management, personnel and customers are located in another country. In that situation, foreign tax authorities may argue that the company is managed elsewhere or that its income should be attributed to another jurisdiction.
An Authorised Company may not satisfy a business that requires Mauritian tax residence or treaty access. Conversely, a Global Business company may be unnecessarily complex where the business does not require treaty positioning or local management.
The jurisdiction should also be approached cautiously by businesses whose activities fall outside the risk appetite of Mauritian banks or regulators. Incorporation without an achievable banking and compliance strategy can leave the company legally established but commercially unusable.
A successful Mauritius structure begins with a defined business function. The company may coordinate African investments, provide regional services, manage an international portfolio, conduct qualifying trade or operate within the country’s regulated financial ecosystem.
Its legal form, tax residence, governance, banking arrangements and level of substance should be designed around that function.
CFA Intelligence supports international businesses in assessing whether Mauritius is appropriate for their objectives and in coordinating the formation, licensing, banking and compliance elements of the structure. The process begins with the ownership model, expected income and transaction flows rather than with an assumed tax rate.
Mauritius can provide a credible and competitive platform for international business, but its advantages are strongest when supported by real management, transparent operations and a commercial strategy capable of standing independently from the tax result.
Additional perspectives on international structuring,banking, compliance and regulatory developments.