Build your business in a transparent, internationally connected jurisdiction with strong governance, modern corporate infrastructure and direct access to Asia-Pacific markets.
New Zealand combines institutional stability, a transparent legal system and an internationally respected business environment. Its modern corporate framework supports companies operating across technology, professional services, international trade, agriculture, advanced manufacturing, renewable energy and other knowledge-driven sectors. The jurisdiction is particularly relevant for founders and international groups seeking a credible presence in the Asia-Pacific region. Company administration is highly digitalised, corporate information is maintained through a public register, and the legal framework provides clear responsibilities for directors and shareholders. However, New Zealand should not be treated as a purely formal registration destination. A successful structure requires a compliant resident director arrangement, genuine governance, appropriate tax positioning and a business model that banks, regulators and commercial partners can understand.
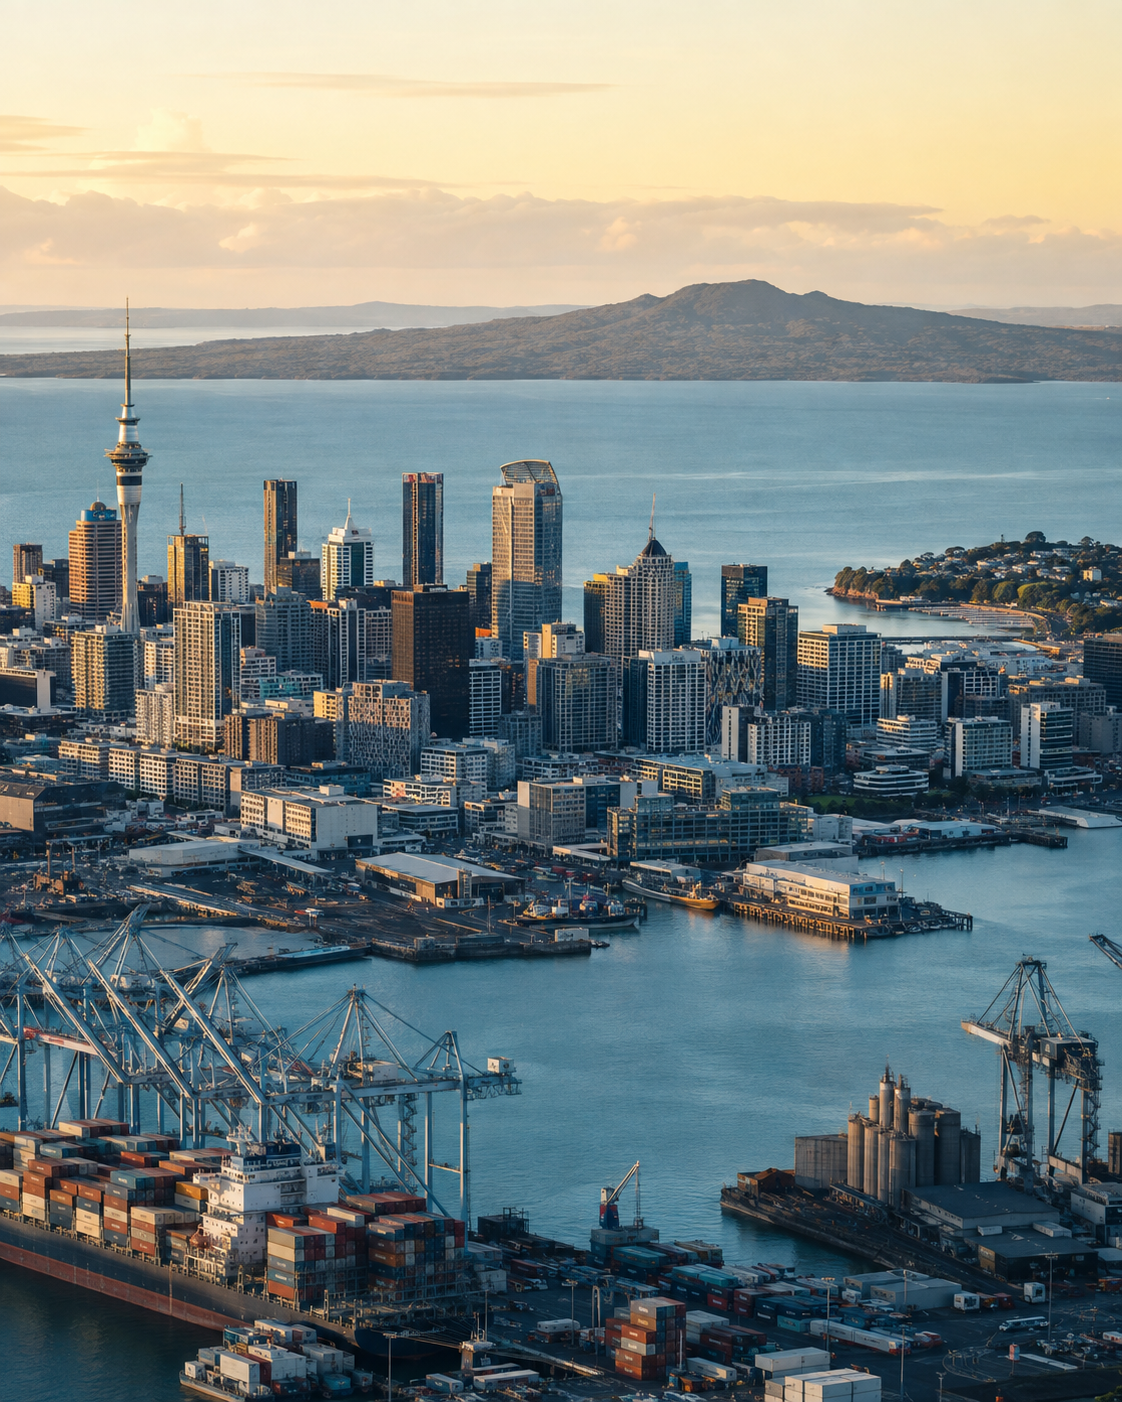
New Zealand offers a combination of commercial credibility, regional connectivity and clear corporate regulation for internationally focused businesses.
New Zealand has built its international reputation around regulatory clarity, institutional reliability and the consistent application of commercial law. These characteristics make the jurisdiction attractive to founders, investors and established groups that value long-term predictability over short-term structural advantages.
The country operates under a common-law legal system and maintains established frameworks for corporate governance, taxation, employment, consumer protection and financial regulation. Corporate information is available through the New Zealand Companies Register, enabling counterparties to verify company status, directors, shareholders and registered details.
This transparency can strengthen confidence during commercial negotiations, supplier onboarding, investment reviews and banking due diligence. It also creates a higher standard of responsibility. Directors must understand their duties, company information must remain current, and the structure must reflect how the business actually operates.
New Zealand is geographically positioned within the Asia-Pacific economy and maintains extensive commercial relationships with Australia, China, Southeast Asia, the United Kingdom, the European Union and other major markets.
Its network of trade agreements includes the Comprehensive and Progressive Agreement for Trans-Pacific Partnership, the Regional Comprehensive Economic Partnership and bilateral arrangements with important global trading partners. These agreements may reduce barriers for qualifying goods and services, provide greater certainty for investors and support participation in regional supply chains.
The commercial value of this network depends on the company’s actual operations. Incorporating a company does not automatically provide access to every trade benefit. Product origin, customs classification, supply-chain structure, local activity and sector-specific requirements must all be considered.
For businesses that genuinely operate from New Zealand or use the country as part of a wider regional strategy, the jurisdiction can provide a credible base for exports, technology development, professional services and cross-border partnerships.
The New Zealand limited company is the most common structure for establishing an independent local business. It creates a separate legal entity and generally limits shareholder liability to the obligations connected with their shares.
An overseas company may alternatively register its New Zealand operations as a branch. A branch does not create a separate legal entity, meaning the overseas parent remains directly responsible for the activities and liabilities of the New Zealand operation.
The choice between a subsidiary and a branch should be based on more than registration speed. Important considerations include:
A subsidiary may provide clearer separation between the New Zealand operation and the wider international group. A branch may be appropriate when the local operation is intended to remain closely integrated with the foreign parent. The correct approach depends on the business model and the role New Zealand will perform within the wider structure.
The incorporation process is administered through the New Zealand Companies Office. A proposed company name must first be reserved, followed by the submission of the company’s directors, shareholders, shares and registered addresses.
Every New Zealand company must have at least one director who lives in New Zealand. Alternatively, the requirement may be satisfied by a director who lives in Australia and is also a director of an Australian-incorporated company.
The company must maintain a registered office and an address for service in New Zealand. Director and shareholder consent forms must also be completed as part of the incorporation process. A company constitution is optional for many limited companies but may be advisable when ownership rights, reserved decisions, share classes or investment arrangements need to be documented more precisely.
Once incorporated, the company receives a New Zealand Business Number. Registration creates the legal entity, but it does not complete the operational setup. Tax registration, accounting, contracts, insurance, employment procedures, banking and any necessary licences must be addressed separately.
Most New Zealand companies are subject to corporate income tax at a rate of 28%. The actual tax position depends on the company’s residence, sources of income, deductible expenses, international transactions and any applicable double tax agreement.
A company incorporated in New Zealand may be treated as a New Zealand tax resident, but cross-border management can create additional questions. The location of directors, strategic decision-making, employees, contracts and commercial activity should therefore be aligned with the intended tax position.
Goods and services tax is generally charged at 15%. Registration becomes mandatory when taxable turnover reaches or is expected to reach NZD 60,000 within the relevant twelve-month period. Voluntary registration may be possible below this threshold when the statutory conditions are satisfied.
International groups must also consider transfer pricing, withholding taxes, controlled foreign company rules and the tax treatment of dividends, interest, royalties and management charges. Tax planning should be supported by commercial logic and documented transactions rather than relying only on the place of incorporation.
New Zealand has a developed banking system and established payment infrastructure. A New Zealand company may apply for local business banking, merchant facilities and international payment services, but incorporation does not guarantee approval.
Banks assess the complete risk profile of the company. This normally includes the identities and backgrounds of shareholders and directors, the source of funds, expected transaction flows, countries involved, customer and supplier relationships and the commercial purpose of the account.
Companies managed entirely from overseas may face additional questions. A credible banking application should demonstrate why the company is incorporated in New Zealand, how it is managed, where its customers are located and what operational connection exists to the jurisdiction.
Banking strategy should therefore be developed alongside the corporate structure. The entity, contracts, website, invoicing model and payment flows should present one consistent commercial story.
New Zealand supports a diverse economy with internationally recognised capabilities in agricultural technology, food production, software, digital services, renewable energy, specialised manufacturing, tourism, healthcare and creative industries.
Its relatively compact domestic market can provide an effective environment for testing products, refining services and building partnerships before expanding into larger Asia-Pacific markets. The country’s reputation for quality, sustainability and responsible governance can also support companies whose commercial positioning depends on trust.
New Zealand is particularly relevant for technology businesses, exporters, professional service providers, research-led ventures and international groups establishing a genuine regional operation.
The jurisdiction may be less appropriate for businesses seeking only a passive registered address without management, personnel, commercial activity or a defensible strategic reason for incorporating there.
Foreign shareholders can participate in New Zealand companies, but certain investments are subject to additional review. Overseas investment consent may be required for sensitive land, fishing quota or significant business assets.
The requirement depends on the investor, the value and nature of the transaction and the assets involved. Investment screening should therefore be considered before acquiring property, infrastructure, strategically important assets or a substantial New Zealand business.
Regulated sectors may require separate registrations, licences or approvals. Financial services, investment products, lending, insurance, telecommunications, healthcare and other controlled activities cannot be conducted solely on the basis of company incorporation.
The regulatory assessment should take place before contracts are signed or services are promoted. This prevents a company from being registered under an operating model that cannot legally be implemented.
New Zealand is not a jurisdiction designed for anonymous or purely nominal corporate arrangements. Public registration, director obligations, tax reporting and banking controls require the structure to remain transparent and commercially coherent.
Substance does not always mean maintaining a large physical office. Its appropriate level depends on the company’s activities. However, the business should be able to demonstrate where decisions are made, who manages operations, where services are delivered and how the New Zealand company contributes to the wider business.
Board records, contracts, accounting documentation, local professional support and properly defined responsibilities help establish this operational credibility. For international groups, the New Zealand company should have a clear purpose within the ownership and transaction structure.
Every New Zealand company must complete an annual return with the Companies Office. This confirms that the information recorded on the Companies Register remains accurate. The annual return is separate from the company’s tax return.
Changes involving directors, shareholders, registered addresses and other company information must be reported within the applicable deadlines. The company must also maintain accounting records, file tax returns and meet its GST, payroll and employer obligations where relevant.
Certain large companies, overseas companies and entities operating within regulated sectors may be subject to additional financial reporting or audit requirements.
Strong compliance should be treated as a continuous management function. Delayed filings, inconsistent records or unexplained transactions can affect the company’s legal standing, banking relationships and commercial reputation.
New Zealand may be suitable for:
The jurisdiction is most effective when incorporation is supported by a credible commercial purpose and a realistic operational plan.
Company formation should be approached as part of a broader business architecture decision. The legal entity must align with ownership, management, taxation, banking, contracts and the company’s intended markets.
CFA Intelligence supports international founders and corporate groups throughout the establishment process, including:
Our objective is not simply to register a company. It is to build a structure that can operate, demonstrate credibility and support sustainable international growth.
Planning to establish a company in New Zealand? Contact CFA Intelligence to discuss the appropriate corporate, banking and compliance framework for your business.
Additional perspectives on international structuring,banking, compliance and regulatory developments.