Establish a commercially credible base in one of Africa’s most developed corporate and financial ecosystems, supported by sophisticated banking, diverse industries and access to regional markets.
South Africa occupies a distinctive position within the international business landscape. It combines a substantial domestic market with developed financial institutions, established corporate law, extensive professional services and commercial connections across the African continent. The country supports businesses operating in manufacturing, mining, financial services, technology, logistics, renewable energy, agriculture, tourism, telecommunications and professional services. It is also home to the Johannesburg Stock Exchange, major regional banking groups and a mature legal and accounting sector. For international investors, South Africa can function as a headquarters, operating subsidiary, distribution centre, manufacturing location or regional service platform. However, it is not a passive or light-touch jurisdiction. Companies must address corporate governance, taxation, beneficial ownership, banking documentation, exchange-control procedures, employment obligations and Broad-Based Black Economic Empowerment considerations. The jurisdiction is therefore most effective for businesses with a genuine commercial strategy, suitable local governance and a clear understanding of their ongoing regulatory responsibilities.
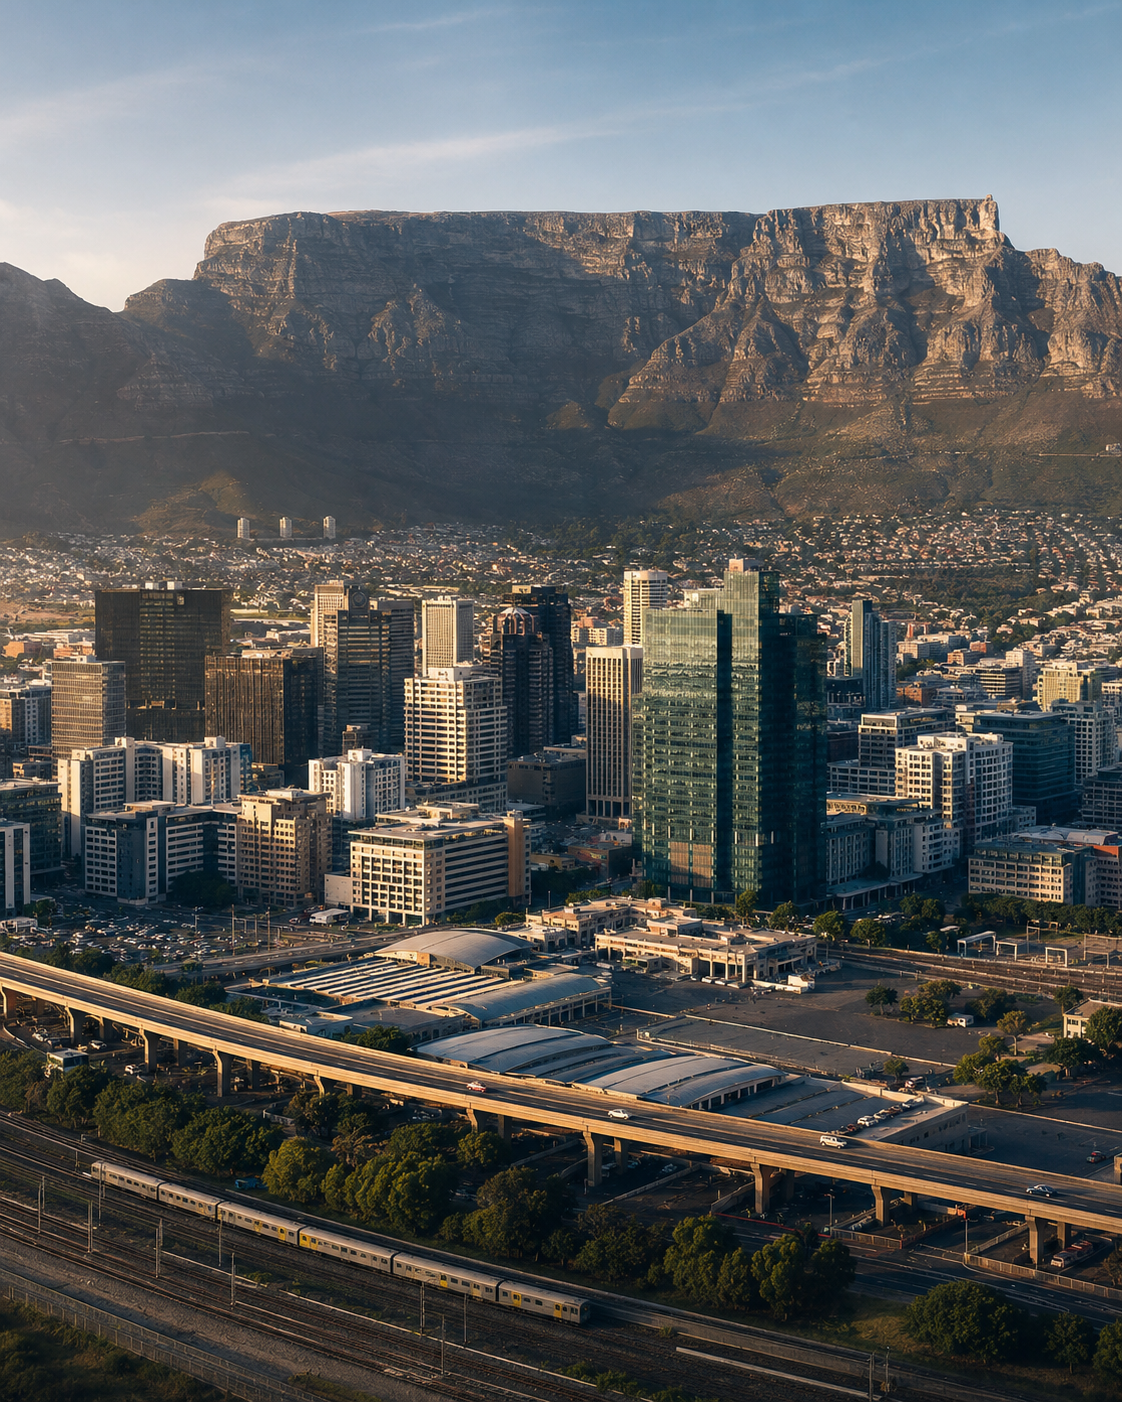
South Africa offers the institutional capacity, commercial depth and regional connectivity required for substantive African operations.
South Africa is frequently selected as a base for businesses expanding across Southern Africa and the wider continent. Its location, transport infrastructure, financial system and regional commercial relationships allow companies to coordinate cross-border activities from an established operating environment.
Johannesburg is an important financial and corporate centre, while Cape Town has developed strong technology, financial services, tourism and creative-sector ecosystems. Durban provides access to major maritime and logistics infrastructure, and other provinces offer specialised opportunities in mining, agriculture, automotive production, energy and industrial development.
South Africa’s participation in regional and continental trade arrangements can support access to neighbouring markets, although tariff treatment, customs procedures and rules of origin must be reviewed for each product and transaction.
A South African entity may therefore be used to manage regional distribution, procurement, professional services, technology operations, manufacturing or investment activities. The structure should reflect the company’s actual supply chains, customer locations and management functions rather than being established solely for geographic positioning.
The private company, identified by the suffix “(Pty) Ltd”, is the structure most frequently used by international investors.
A private company is a separate legal entity whose shareholder liability is generally limited to the capital invested. It may be wholly or partially owned by foreign shareholders and can operate as a subsidiary of an international group.
Its constitutional framework is established through a Memorandum of Incorporation. This document regulates matters such as the company’s share structure, director authority, governance procedures and restrictions on the transfer of securities.
A foreign company may alternatively register an external company, commonly referred to as a branch, when it conducts business in South Africa without incorporating a separate local subsidiary. A branch remains legally connected to its foreign head office, which can expose the parent organisation directly to liabilities arising from South African operations.
The choice between a subsidiary and a branch should be based on liability protection, taxation, banking, commercial credibility, regulatory exposure and the intended duration of the South African activity.
Companies are registered through the Companies and Intellectual Property Commission, or CIPC.
A private company must have at least one director. Its incorporation process generally requires an approved company name or registration under its assigned enterprise number, a registered address, director information, identification documents and a Memorandum of Incorporation.
Foreign directors and shareholders may participate, but additional identification and verification procedures can apply. Documents issued outside South Africa may require certification or other formal authentication.
The company must maintain accurate registers of directors, shareholders and beneficial owners. Beneficial ownership information is filed with CIPC and must be updated when relevant changes occur and as part of the company’s annual compliance process.
A South African company that is liable for tax must also appoint an appropriate public officer or registered representative for its interactions with the South African Revenue Service. This position should be established early because it affects tax registration, access to the SARS system and ongoing return filing.
Governance should not be treated as a registration formality. Director responsibilities, signing authority, shareholder protections and group reporting lines should be documented before operations begin.
South African resident companies are generally subject to corporate income tax on their worldwide taxable income, with relief potentially available under domestic legislation or an applicable double taxation agreement.
The standard corporate income tax rate is 27%. Taxable profit is calculated according to South African tax legislation rather than simply by applying the rate to accounting income.
Companies may also need to consider:
Value-added tax is generally charged at 15% on taxable supplies. From 1 April 2026, compulsory VAT registration generally applies when taxable supplies exceed the prescribed annual threshold of R2.3 million. Voluntary registration may be available when the relevant requirements are met.
Businesses should assess their VAT position before issuing invoices or entering long-term contracts. Registration timing, input tax recovery, imported services, electronic services and cross-border supplies can materially affect pricing and cash flow.
South Africa has a broad double taxation agreement network, but treaty benefits are not automatic. The company must satisfy the relevant residence, beneficial ownership, substance and documentation requirements.
South Africa has one of the continent’s most developed banking systems. Its major banks provide domestic and international payments, corporate accounts, lending, trade finance, treasury services and foreign-exchange facilities.
Bank account opening is nevertheless subject to detailed customer due diligence. Banks may request:
Banking should therefore be approached as a compliance project rather than an automatic consequence of company registration.
Cross-border capital movements and foreign-exchange transactions operate within South Africa’s financial surveillance framework. Relevant payments are normally processed through an Authorised Dealer, typically a registered bank.
The company should properly document foreign investment, shareholder funding, intercompany loans, dividends, royalties, management fees and other international payments. Incorrectly structured capital or incomplete supporting documentation can delay future transfers and create tax or regulatory complications.
Broad-Based Black Economic Empowerment, commonly known as B-BBEE, is an important component of South Africa’s commercial and regulatory environment.
B-BBEE is intended to expand economic participation and address historical inequalities. Its practical impact varies according to the company’s size, sector, customers and activities.
A company’s B-BBEE position can influence:
Foreign ownership is not generally prohibited merely because a company does not have black shareholders. However, ownership can be a significant component of the applicable B-BBEE scorecard, alongside management control, skills development, enterprise and supplier development, and socioeconomic development.
International groups should assess B-BBEE at the planning stage. The appropriate strategy may involve local participation, workforce development, supplier programmes, sector-specific arrangements or, where available, recognised equity-equivalent initiatives.
The objective should be to create a structure that is commercially credible, legally compliant and consistent with the group’s long-term South African strategy.
South Africa has a diverse economy that supports both service-based and asset-intensive businesses.
The country has established capabilities in:
Its developed professional ecosystem allows international companies to access legal, accounting, engineering, technology and financial expertise locally.
Special Economic Zones and sector-specific programmes may provide infrastructure, customs support or investment incentives for qualifying projects. Eligibility depends on the location, industry, expenditure profile, employment commitments and other programme conditions.
Incentives should strengthen an independently viable business model. They should not be treated as a substitute for market demand, reliable infrastructure, sufficient working capital or effective operational management.
South Africa is generally open to foreign investment, and international shareholders may establish and own local companies.
However, regulated industries can require additional approvals, registrations or ownership arrangements. These may include financial services, mining, energy, telecommunications, healthcare, pharmaceuticals, food production, transport and certain environmental activities.
A standard company registration does not authorise the entity to conduct every proposed business activity. Sector analysis should therefore take place before incorporation, especially where the project requires land use approvals, environmental authorisations, operating licences or professional registrations.
Competition-law approval may also be relevant to acquisitions, mergers and certain joint ventures. Transactions involving strategically important businesses or sensitive industries may attract additional regulatory review.
Foreign executives and employees must hold appropriate immigration and work authorisation. Company ownership or appointment as a director does not by itself provide permission to work or reside in South Africa.
A South African entity should have operational substance appropriate to its purpose.
Substance may include:
Management location is important when assessing tax residence and treaty access. A company incorporated outside South Africa may still create South African tax exposure if its effective management or business activities are located in the country.
Transactions between related parties must generally follow arm’s-length principles. Intercompany loans, service charges, royalties, procurement arrangements and management fees should be supported by agreements, commercial evidence and transfer-pricing analysis.
Artificial arrangements, unsupported charges and structures without genuine commercial functions can be challenged by tax authorities and financial institutions.
Companies employing personnel in South Africa must address employment contracts, payroll administration, employee tax, unemployment insurance, compensation obligations and applicable labour standards.
South African labour law provides meaningful protections to employees. Hiring, restructuring and termination processes should therefore be planned with appropriate legal and human-resources support.
Businesses may also need to comply with workplace safety, data protection, consumer protection and industry-specific requirements.
The Protection of Personal Information Act establishes obligations concerning the collection, use, retention and protection of personal information. Companies processing customer, employee or supplier data should implement suitable privacy notices, agreements, security controls and internal policies.
South African companies must maintain proper accounting and corporate records and complete recurring filings with CIPC and SARS.
Typical obligations may include:
The required level of financial reporting, independent review or audit depends on the company’s legal status, Memorandum of Incorporation, Public Interest Score and other statutory criteria.
Failure to file annual returns can lead to penalties and eventual deregistration. Inaccurate beneficial ownership information, overdue tax filings or inconsistent company records can also affect banking, transactions and regulatory approvals.
A compliance calendar should be established immediately after incorporation and coordinated between the company’s directors, accountants, tax advisers and corporate administrator.
South Africa may be suitable for:
It may be less appropriate for businesses seeking only nominal registration, minimal reporting or an offshore company without local activity.
The jurisdiction delivers its strongest value when the company has an identifiable commercial role, appropriate capital, effective governance and a realistic plan for operating within South Africa’s regulatory environment.
South Africa offers substantial commercial opportunities, but successful establishment requires more than registering a company.
CFA Intelligence supports international clients throughout the formation and operational process, including:
Our objective is to create a South African structure that is commercially practical, properly governed and capable of supporting sustainable local and regional operations.
Additional perspectives on international structuring,banking, compliance and regulatory developments.