The United Arab Emirates has developed into a sophisticated international business jurisdiction combining regional market access, advanced infrastructure, diverse corporate environments and a competitive framework for cross-border investment. Its seven emirates and numerous specialised free zones allow international companies to select a structure aligned with their industry, operating model and long-term commercial objectives.
The United Arab Emirates is not a single uniform corporate location. It is a federation of seven emirates-Abu Dhabi, Dubai, Sharjah, Ajman, Umm Al Quwain, Ras Al Khaimah and Fujairah-each contributing different commercial capabilities, licensing environments and sector ecosystems to the wider national economy. This creates a level of choice that distinguishes the UAE from many other jurisdictions. International companies can establish mainland operations, enter specialised free zones, build regional headquarters, develop trading and logistics functions or create structures serving technology, manufacturing, investment and professional services activities. The breadth of options is also what makes proper planning essential. A company established for international consulting will have different requirements from an industrial business, regional distributor, holding company or regulated financial institution. The appropriate emirate, licensing authority, corporate form and tax treatment must therefore be selected around the real business model rather than around the apparent simplicity or cost of an incorporation package.
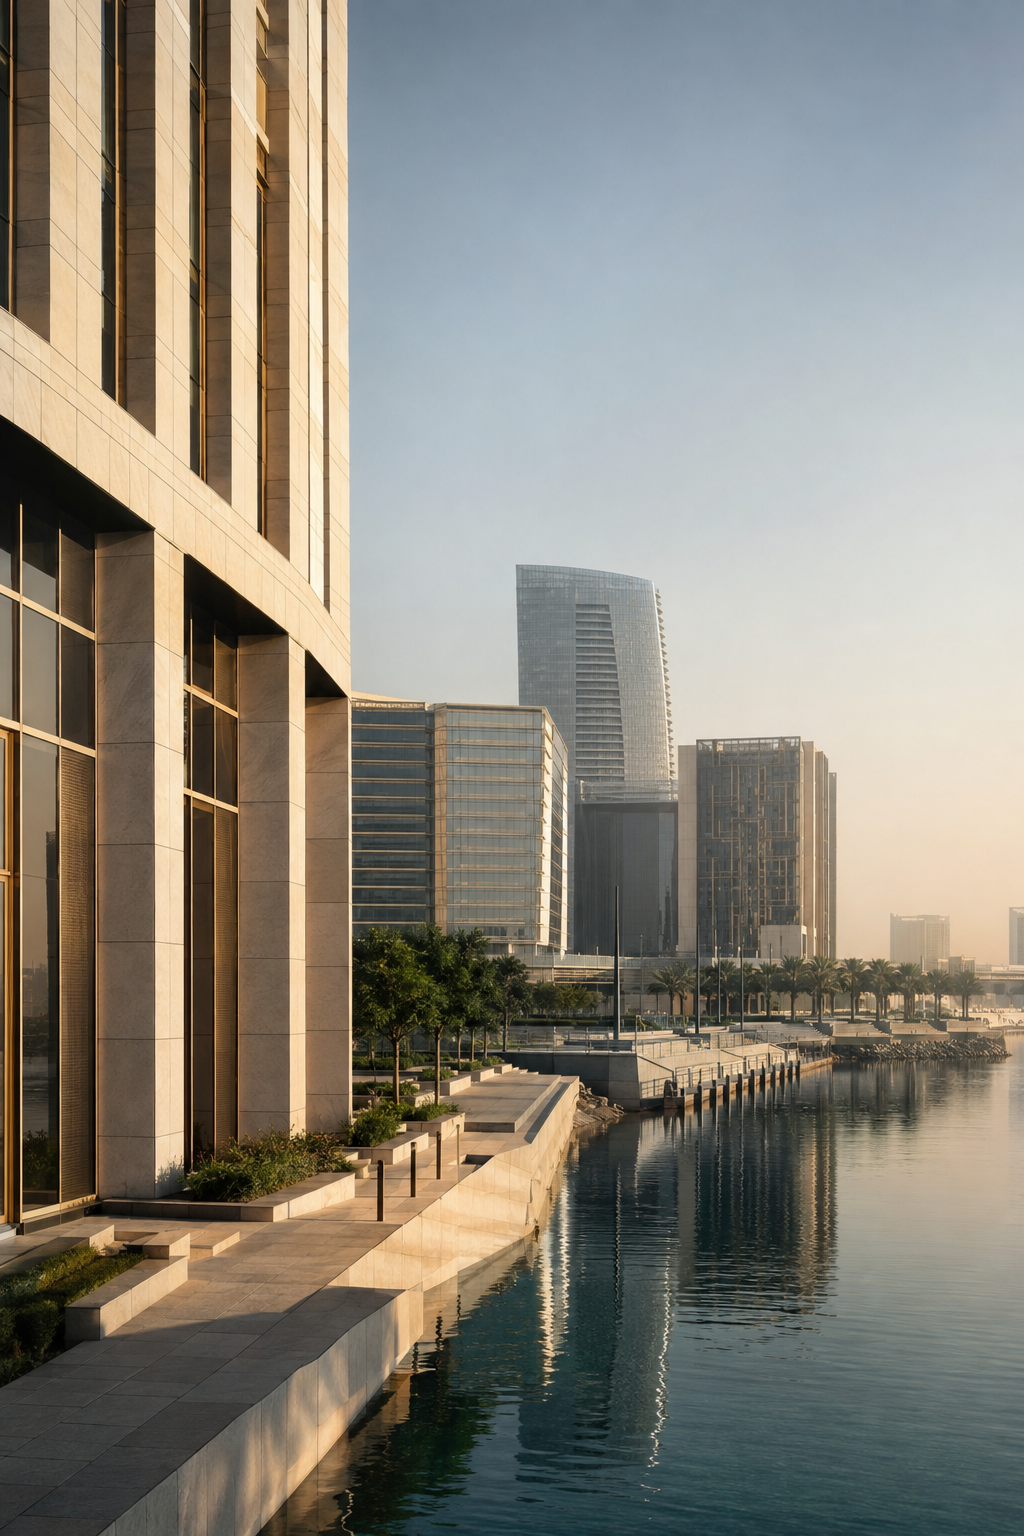
The UAE combines international connectivity with a diverse corporate environment capable of supporting companies at different stages of regional and global expansion.
Business establishment in the UAE operates across several interconnected levels. Federal legislation shapes areas such as corporate taxation, commercial companies, beneficial ownership, employment and anti-money laundering obligations. At the same time, individual emirates and free zone authorities manage the licensing and administration of companies established within their respective jurisdictions.
This means that two UAE companies may operate under significantly different practical conditions even when their shareholders and activities appear similar. Licensing costs, permitted activities, premises requirements, visa allocations, regulatory approvals and access to particular markets may vary according to the chosen authority.
The structure should begin with a clear understanding of what the company will actually do. Its customers, suppliers, contracts, employees, management functions, physical operations and expected financial flows should all be considered before the jurisdiction is selected. In the UAE, the quality of the initial structural decision can materially affect banking, taxation, compliance and the company’s ability to expand.
Mainland companies are licensed by the competent economic authority in the relevant emirate. They are generally considered by businesses intending to operate directly within the wider UAE market, maintain a conventional local presence, work with a broad range of domestic customers or participate in commercial activities that are more naturally conducted through a mainland structure.
Changes to the UAE commercial companies framework have enabled full foreign ownership across a broad range of mainland activities, although specific conditions and restrictions may continue to apply to strategically important or regulated sectors. The precise ownership and approval requirements must therefore be verified against the selected activity and emirate. The official UAE Government platform provides current information on foreign ownership and mainland establishment.
Free zones operate through their own authorities and may be organised around industries such as finance, commodities, logistics, media, technology, healthcare, manufacturing or international services. They can provide streamlined administration, specialised infrastructure and access to relevant professional communities.
However, free zones are not interchangeable. A prestigious financial centre, an industrial zone and a broadly accessible commercial free zone serve very different purposes. Their rules governing activities, premises, audits, share capital, staffing and interaction with the mainland may also differ. The establishment decision should therefore be based on operational suitability rather than on the term “free zone” alone.
Different emirates have developed distinct commercial strengths. Abu Dhabi supports major energy, industrial, financial, investment and technology initiatives, while Dubai has become internationally recognised for trade, logistics, tourism, finance, professional services and digital business. Sharjah has significant manufacturing, education and creative-sector capabilities, while Ras Al Khaimah and other emirates provide corporate environments relevant to industrial, trading, logistics and internationally managed businesses.
These distinctions should not be reduced to a simple comparison of incorporation prices. The most appropriate location depends on the company’s industry, customers, required facilities, management plans and access to specialised regulators or counterparties.
A company expecting to establish a regional team may prioritise talent availability, transport connectivity and suitable office infrastructure. A manufacturer or distributor may place greater importance on industrial facilities, ports, warehousing and customs arrangements. A financial or virtual asset business must begin with the regulatory perimeter and the availability of the required licence.
The chosen emirate should perform a clear role within the company’s wider strategy. When the jurisdiction is aligned with the business model, the UAE entity becomes more than a registration vehicle: it becomes an operational part of the international group.
A UAE company is authorised to conduct the activities specified in its licence. Selecting the correct activity is therefore one of the most important parts of the establishment process.
Broad commercial descriptions may conceal important distinctions. Software development, IT consulting, digital marketing, management consultancy and e-commerce may require different activities even when they form part of the same wider business. Trading companies must consider the categories of goods involved, while professional and regulated services may require approvals from additional authorities.
The legal form must also support the intended ownership, governance and investment model. Depending on the jurisdiction and purpose, the available options may include limited liability companies, free zone companies, branches and other specialised vehicles. Holding, special-purpose and foundation structures may also be available within particular financial or corporate centres.
Licensing should be consistent with the company’s website, contracts, invoices and transaction profile. Misalignment between the declared activity and the actual business can create difficulties with banks, regulators, payment providers and commercial counterparties.
The UAE’s geographic position allows companies to coordinate commercial relationships across several major regions. Its airports, ports, logistics networks and professional services ecosystem support international trade, regional distribution and cross-border management.
For many businesses, the UAE can function as a regional headquarters or a commercial bridge between Europe, Asia, Africa and the Middle East. Companies may use the jurisdiction to manage sales, develop partnerships, hold inventory, recruit regional teams or coordinate services delivered across multiple countries.
Establishment in the UAE does not, however, eliminate obligations elsewhere. If a company has employees, offices, management functions or sustained commercial activity in another country, it may create tax, licensing or permanent establishment considerations in that market. The UAE company must therefore be analysed as one component of the wider international structure.
The country’s extensive network of double taxation agreements can support cross-border business, but treaty access is not automatic. It may depend on tax residence, beneficial ownership, substance and the specific provisions of the relevant agreement. The UAE Ministry of Finance maintains official information on the country’s international tax treaty network.
The UAE has an established financial sector that includes domestic and international banks, Islamic financial institutions, payment providers, fintech companies and specialised financial centres. This infrastructure can support corporate accounts, trade finance, multicurrency payments, payroll and regional treasury functions.
Nevertheless, company incorporation does not guarantee account opening. UAE financial institutions are required to conduct customer due diligence and assess the ownership, management, business model, source of funds, expected transactions and jurisdictions connected with the company. Enhanced review may apply where the ownership structure, activity or geographic profile creates additional risk.
A well-prepared banking application should demonstrate a coherent operating model. Corporate documents, licences, websites, shareholder profiles, contracts, financial projections and expected transaction flows should tell the same commercial story. Evidence of local management, premises, employees or existing relationships may also strengthen the company’s profile where these elements are relevant to the business.
Banking requirements should therefore influence the structure from the beginning. Selecting an entity first and only later considering how it will receive or distribute funds can produce unnecessary delays and limitations.
The UAE can no longer be accurately described as a jurisdiction without corporate tax. Federal corporate tax applies to financial years beginning on or after 1 June 2023, bringing UAE businesses within a structured tax, registration and reporting framework.
Under the standard regime, taxable income is generally subject to a 0% rate up to AED 375,000 and a 9% rate above that threshold. Taxable persons are required to register, maintain appropriate financial information and file corporate tax returns within the prescribed period. The official framework is published by the UAE Ministry of Finance.
Free zone companies also fall within the scope of corporate tax. A company meeting the requirements of a Qualifying Free Zone Person may benefit from a 0% rate on Qualifying Income, but this treatment is conditional. It depends on factors including the nature of the income and activities, adequate substance, transfer pricing compliance and satisfaction of the applicable regulatory criteria. Income outside the qualifying framework may be subject to the standard rate.
For large international groups, the UAE Domestic Minimum Top-up Tax must also be considered. It applies to UAE entities belonging to multinational groups meeting the relevant €750 million consolidated revenue threshold and is effective for financial years beginning on or after 1 January 2025. This reflects the UAE’s increasing alignment with international tax standards.
VAT applies at a standard rate of 5%. UAE-resident businesses are generally required to register when taxable supplies and imports exceed AED 375,000, while the treatment of exports, imports, cross-border services and designated zones depends on the nature of the transaction. Tax planning should therefore be based on the company’s actual activities rather than on historic assumptions about the UAE tax environment.
A sustainable UAE structure requires more than an active commercial licence. Companies must maintain appropriate governance, accounting records, beneficial ownership information, tax registrations and regulatory filings.
Substance should reflect the function performed by the UAE entity. Depending on the business, this may involve local management, employees, premises, operational expenditure and evidence that key commercial decisions are genuinely made within the jurisdiction. A company applying a particular free zone tax treatment must pay especially close attention to the substance requirements connected with its qualifying activities and income.
International groups must also consider transfer pricing, related-party transactions and the allocation of income between group entities, branches and permanent establishments. Contracts and financial flows should correspond with the functions, assets and risks of the UAE company.
These requirements do not reduce the UAE’s value as an international jurisdiction. They make the jurisdiction more compatible with the expectations of banks, institutional investors, regulators and sophisticated counterparties. Proper governance strengthens the company’s commercial credibility and supports its ability to grow.
The UAE may be appropriate for companies seeking access to the Gulf region, a base for international trading, a regional management function or an operational presence connecting several markets. It can also support entrepreneurs who intend to relocate, recruit locally or develop meaningful commercial relationships within the country.
The jurisdiction may be less suitable where the proposed entity would have no genuine connection to the UAE, where all management and operations remain in another country, or where the selected licence does not reflect the actual business. It may also be unnecessary for a company whose customers, employees and commercial activity are concentrated entirely within another jurisdiction.
Costs must be evaluated beyond the initial incorporation package. Licence renewal, premises, visas, accounting, tax filings, audit requirements, compliance and banking administration can all form part of the long-term operating budget.
The relevant question is therefore not whether the UAE is generally attractive. It is whether a particular UAE structure supports the company’s real activities more effectively than the available alternatives.
The United Arab Emirates offers one of the most diverse corporate environments available to internationally active businesses. Its combination of regional access, specialised commercial ecosystems, infrastructure and international connectivity can support companies ranging from founder-led businesses to complex multinational groups.
The strongest structures are those designed around commercial reality. The appropriate emirate, licensing authority, corporate form, banking model, tax position and operational substance should work together as parts of a single strategy.
When these elements are aligned, the UAE can provide more than efficient company establishment. It can become a credible long-term platform for management, investment, market access and international growth.
Additional perspectives on international structuring,banking, compliance and regulatory developments.